
2 Year Or 5 Year Mortgage
Mortgage Mayhem: 2 Years or 5? Let's Dish! So, you're in the market for a mortgage, huh? Welcome to the wild world of home loans! Today, we're going to tackle a question that'...
Mortgage Mayhem: 2 Years or 5? Let's Dish!
So, you're in the market for a mortgage, huh? Welcome to the wild world of home loans! Today, we're going to tackle a question that's been keeping homeowners up at night: should you go for a 2-year mortgage or a 5-year one? Buckle up, folks, 'cause we're about to get real. And by real, I mean fun. Like, 'popcorn and Netflix' fun. Let's dive in!
First Things First: What's the Deal with These Mortgages?
Alright, let's start with the basics. A mortgage is like a big, fancy prom date for your house. You promise to take care of it (pay your bills on time), and in return, the bank lets you live in your dream home. Now, these dates come in different flavors: 2-year and 5-year.
Imagine the 2-year mortgage as a fun, spontaneous weekend getaway. It's short, sweet, and full of surprises. On the other hand, a 5-year mortgage is like a well-planned, all-inclusive vacation. It's longer, steadier, and you know exactly what you're getting into. Got it? Good. Now let's get weird.
Must Read
2-Year Mortgages: The Wild Card
Picture this: you're at a casino, and the 2-year mortgage is the roulette table. It's exciting, it's unpredictable, and if you're lucky, you might just hit the jackpot. These mortgages have lower interest rates, which means you pay less each month. But here's the catch: after 2 years, your rate could skyrocket, or it could stay the same. It's a mystery! Isn't that just the best kind of suspense?
Now, you might be thinking, "That sounds like a fun game I don't want to play." And that's okay! But hey, if you're feeling lucky, a 2-year mortgage could be your ticket to saving big bucks. Just remember, fortune favors the bold. Or something like that.
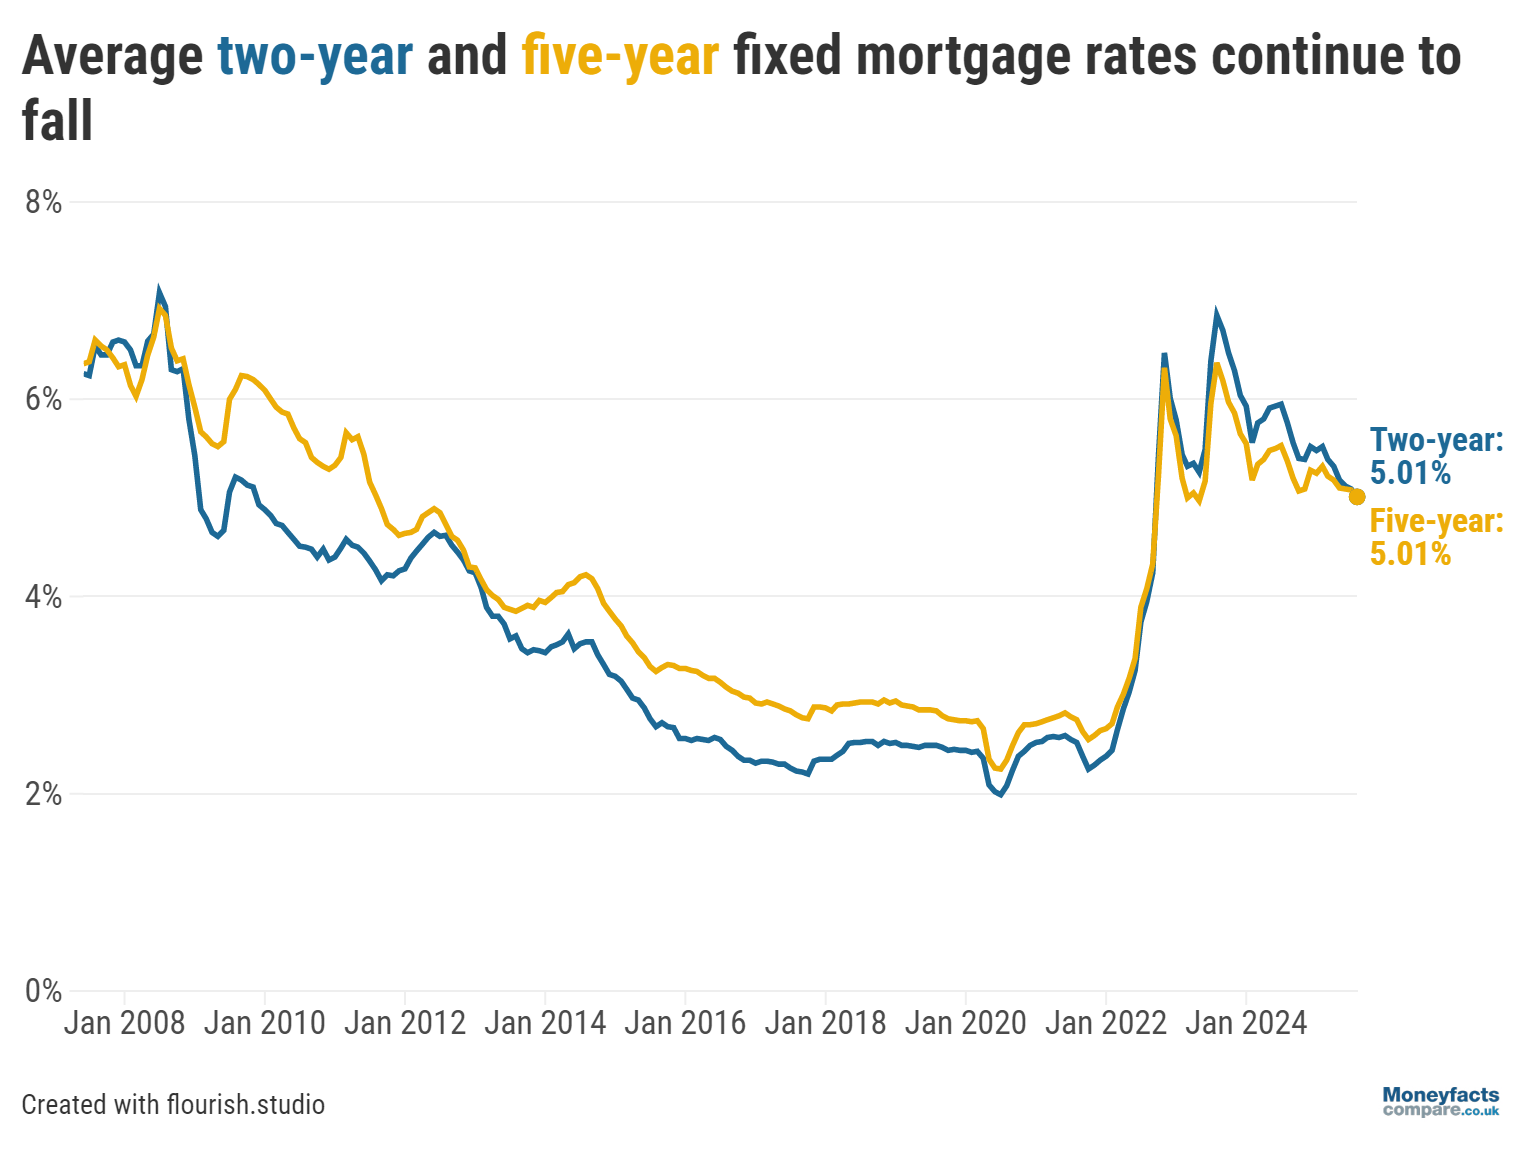
 Two-year UK mortgage rates fall faster than longer-term deals – Home
5-Year Mortgages: The Steady Eddie
Now, let's talk about the 5-year mortgage. This guy is like the dependable best friend who always shows up on time with pizza and a smile. With a 5-year mortgage, you know exactly what you're getting into. Your interest rate stays the same for 5 whole years. No surprises, no mysteries. Just steady, predictable payments.
But here's the thing: those steady payments might be a little higher than the 2-year mortgage. It's like choosing between a fancy, expensive dinner or a bunch of cheap, spontaneous fast-food runs. Both have their perks, right?
So, Which One's Right for You?
Alright, let's get real for a sec. The truth is, neither mortgage is universally 'right.' It all depends on you, your lifestyle, and your financial goals. Are you a risk-taker who loves a good mystery? A 2-year mortgage might be your jam. Or maybe you're more of a planner, someone who likes to know exactly what's coming next. In that case, a 5-year mortgage might be just your cup of tea.
 Mortgage Approvals Rise In March | moneyfactscompare.co.uk
But hey, don't take our word for it. Talk to a financial advisor, crunch some numbers, and see what feels right. And remember, no matter what you choose, you're one step closer to owning your own little slice of the American dream. Isn't that just the coolest?
And That, Folks, is the Tale of the 2-Year and 5-Year Mortgages
So there you have it. The 2-year mortgage: the wild, unpredictable roulette table. The 5-year mortgage: the steady, dependable best friend. Both have their perks, both have their downsides. But at the end of the day, it's all about what works best for you.
Now, go forth, young homeowner. Make your choice, and let the good times roll. And hey, if you ever need a mortgage referee, you know where to find us. Happy home hunting!
