
Bank Of England Interst Rate
Alright, gather 'round, folks. Let's chat about something that might sound as dull as dishwater, but I promise, it's as relevant to your daily life as your morning cuppa. We'r...
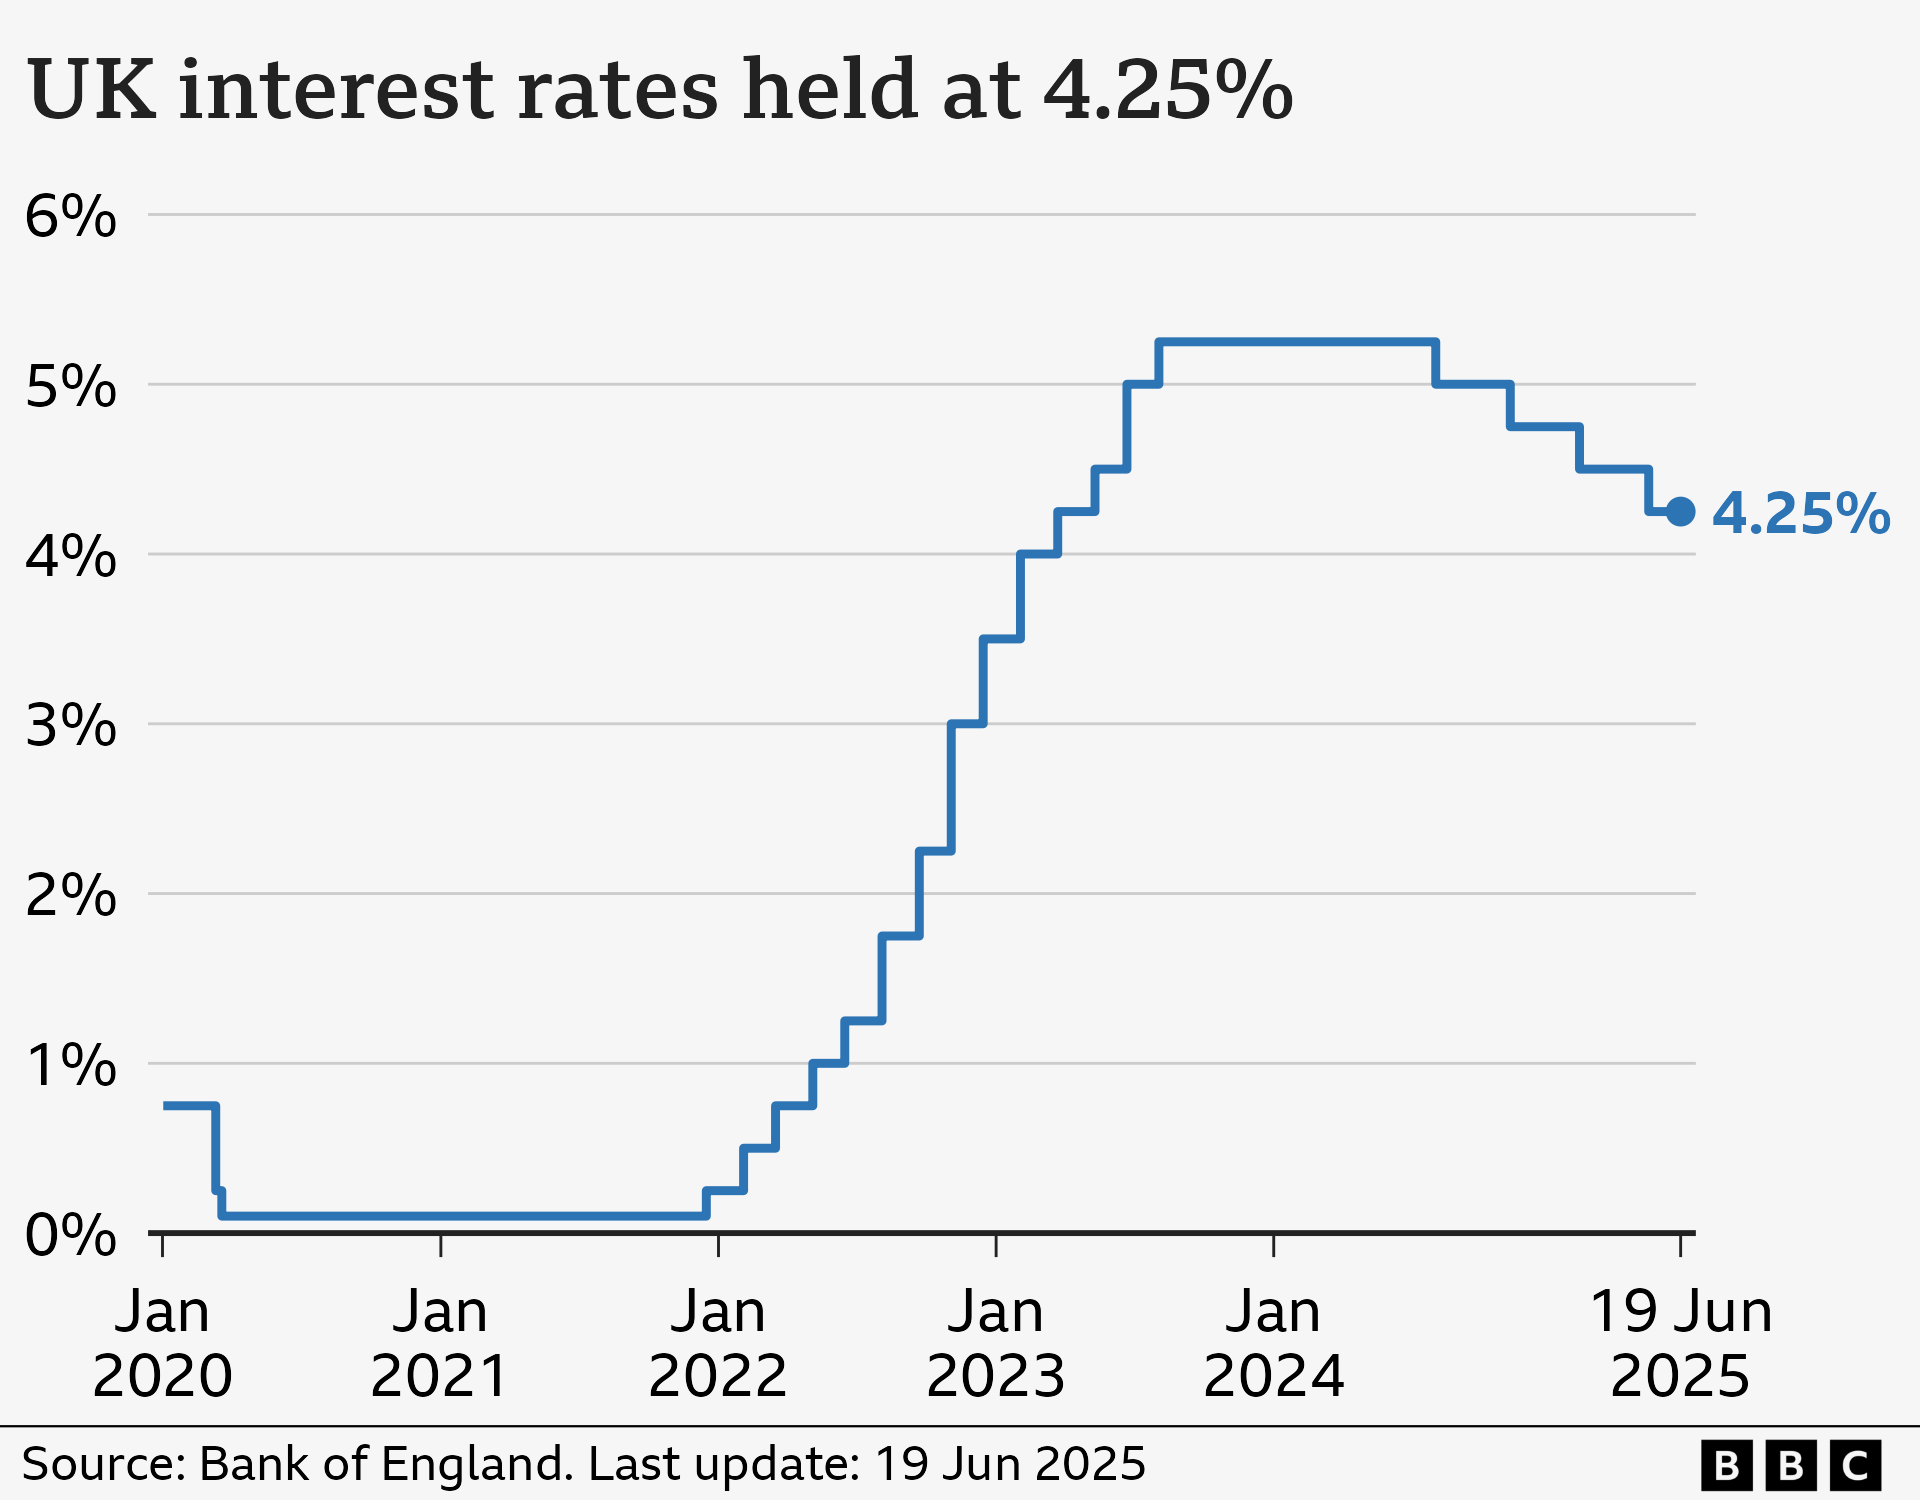
Alright, gather 'round, folks. Let's chat about something that might sound as dull as dishwater, but I promise, it's as relevant to your daily life as your morning cuppa. We're diving into the world of the Bank of England's interest rates. Don't worry, I won't bore you with economic jargon, we're keeping it real and relatable, yeah?
So, what's the big deal about interest rates?
Imagine you're at a mate's house, and they've got a jar of sweets. Now, if they say, "Help yourself, but for every sweet you take, you owe me one later," that's basically what interest rates are like. The Bank of England sets the rate, and when you borrow money, you're 'taking sweets' from the jar, and you've gotta pay back a little extra later.
But why does the Bank of England care about my sweet tooth?
The Bank of England isn't just some bigwig with a sweet jar, it's the central bank of the UK. It's like the parent at the party, making sure everyone's behaving and having a good time, but not getting too carried away. When it changes the interest rate, it's trying to keep the economy in check. Too many people borrowing and spending? It might raise the rate to slow things down. Not enough people spending? It might lower the rate to encourage a bit of retail therapy.
Must Read
Think of it like a game of musical chairs. The Bank of England wants to make sure there's a chair for everyone when the music stops. If too many people are dancing (spending), it might speed up the music (raise interest rates) to make sure not everyone ends up standing (in debt).
But how does this affect my everyday life?
Well, let's say you're thinking about getting a mortgage for your dream home. If the interest rate is high, it's like the bank is saying, "Yeah, we'll lend you the money, but it's gonna cost ya." Your monthly repayments will be higher, and it might take you longer to pay off your mortgage. But if the interest rate is low, it's like the bank is saying, "Sure thing, mate! Here's the keys to your castle, and you can pay us back at a nice, easy pace." Your repayments will be lower, and you'll be mortgage-free sooner.
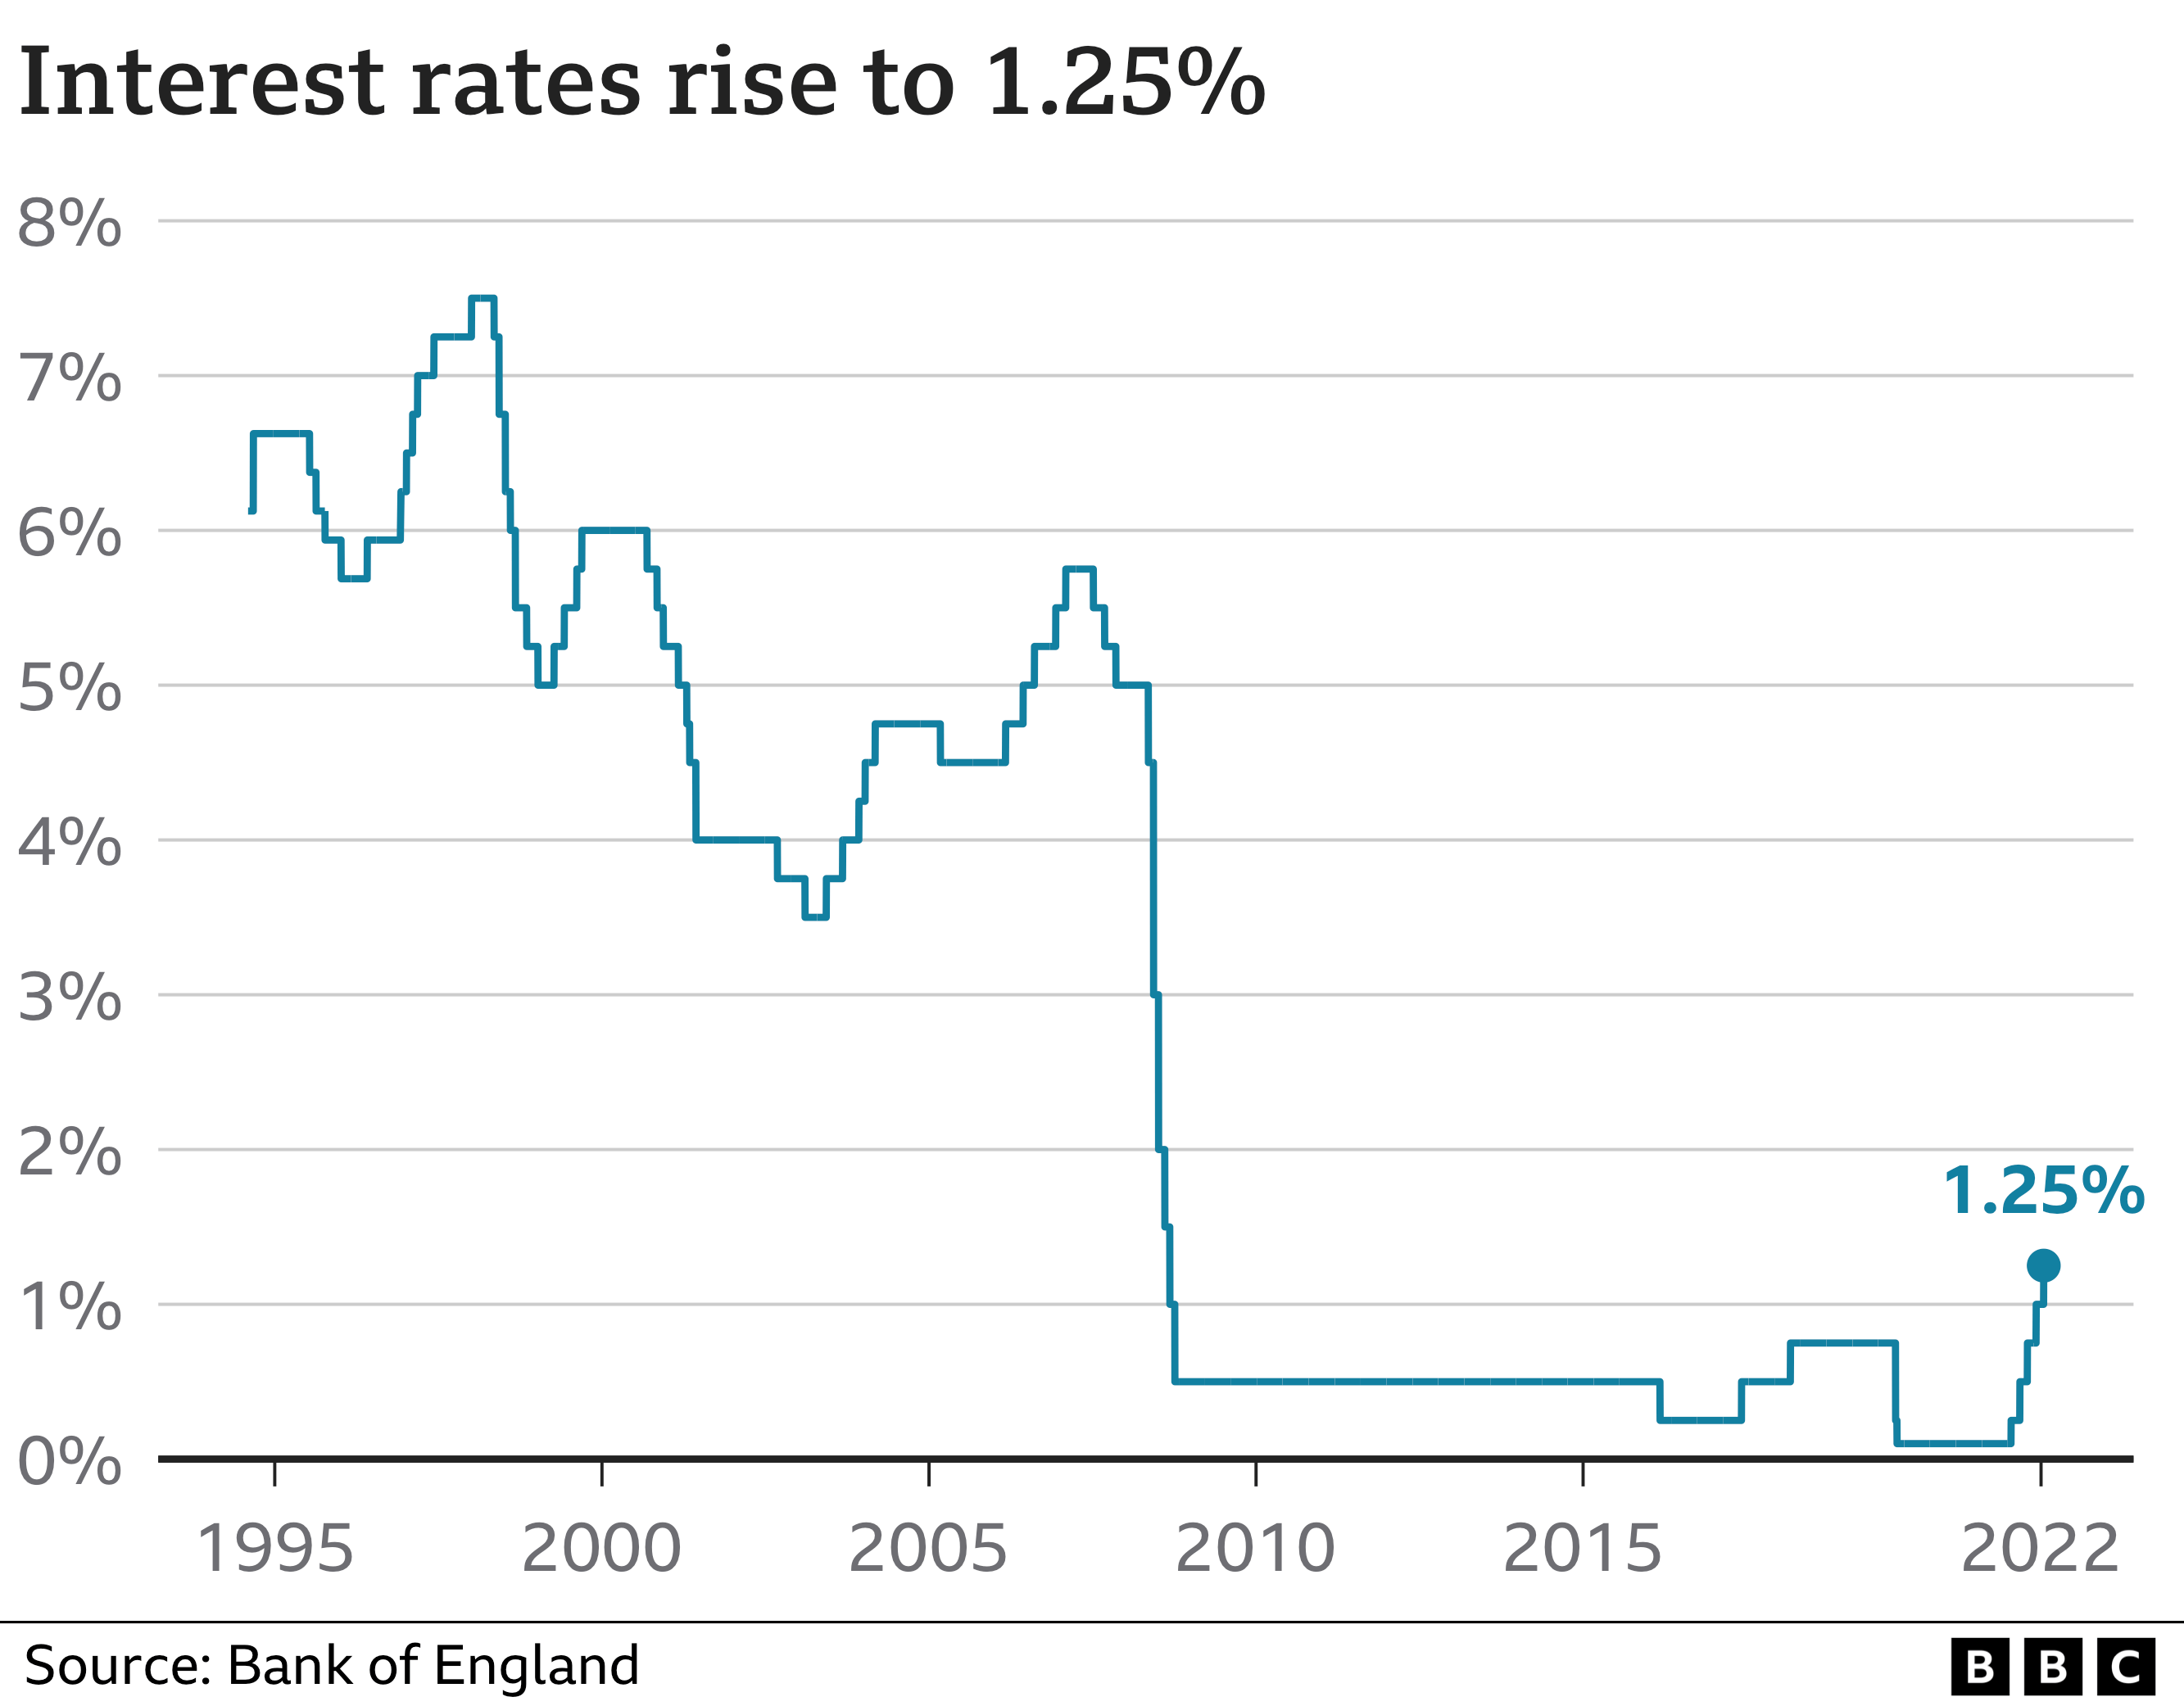 UK interest rates raised to 1.25% by Bank of England - BBC News
The same goes for savings. If the interest rate is high, it's like the bank is saying, "Thanks for saving with us! Here's a little bonus for being such a responsible adult." You'll earn more interest on your savings. But if the interest rate is low, it's like the bank is saying, "Cheers for saving, but we're not exactly rolling in cash to share with you right now." You'll earn less interest, but hey, at least you're not spending all your money on avocado toast, right?
So, should I be dancing faster or slower?
That's the million-dollar question, isn't it? The truth is, no one knows for sure what the Bank of England is going to do with interest rates. It's like trying to guess what your mate's gonna pick for their next song on the party playlist. But that's where financial advisors and economists come in. They're like the party planners, keeping an eye on the Bank of England and trying to predict what's next.
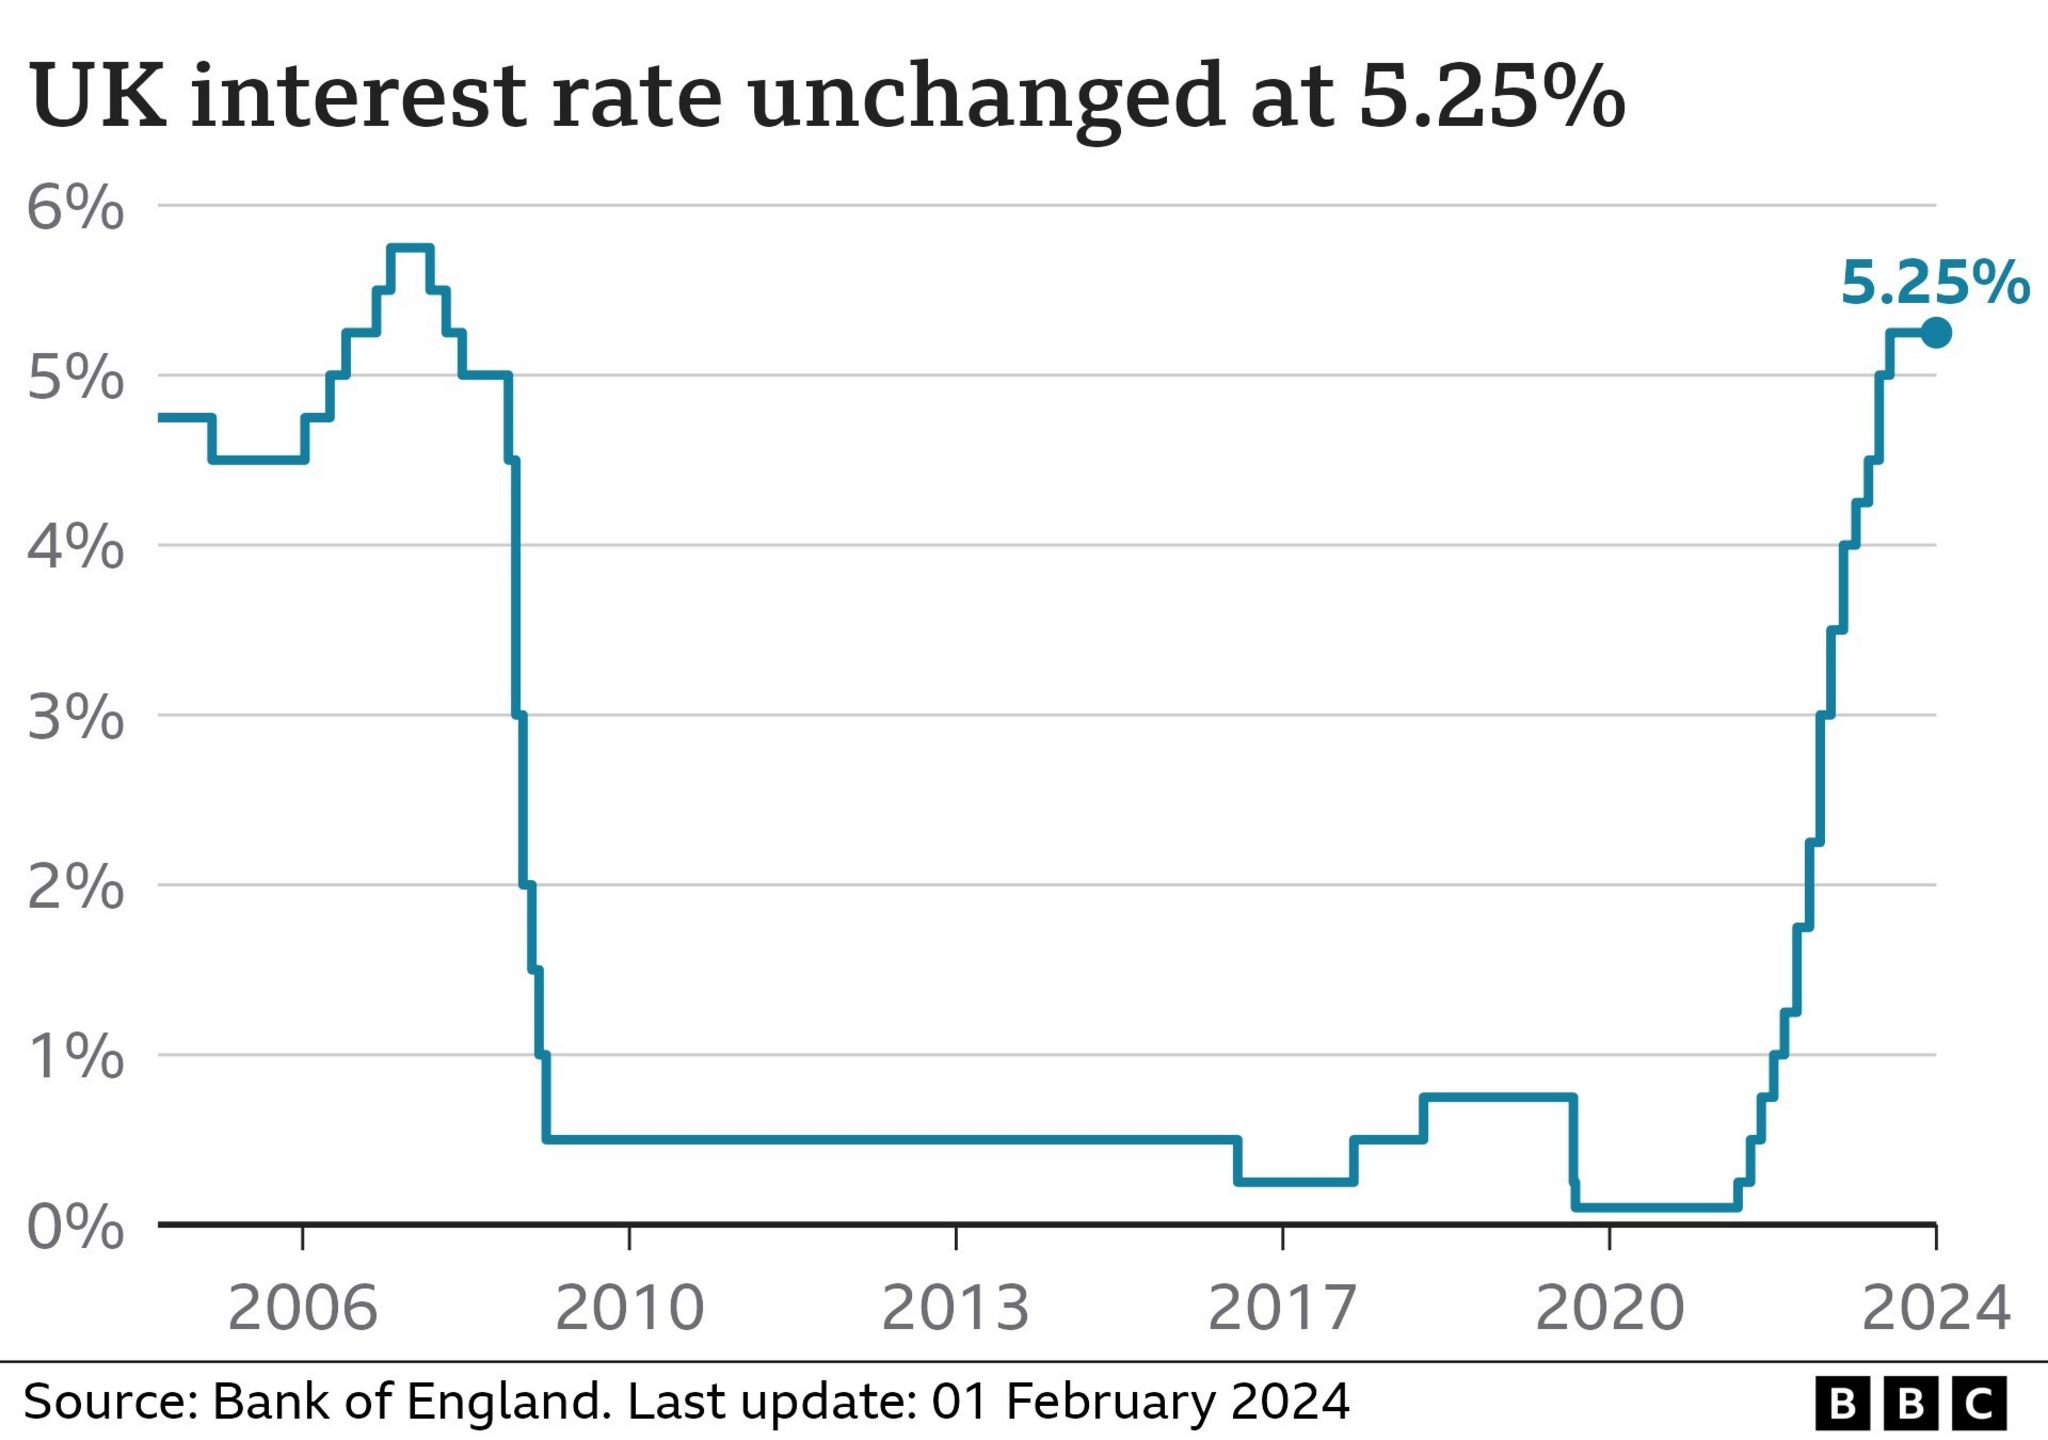 Bank of England moving closer to interest rate cut - BBC News
But remember, folks, this is just a chat. I'm not a financial advisor, and I'm certainly not the Bank of England. I'm just here to help you understand what's going on with interest rates and how it might affect your life. So, the next time you hear about the Bank of England changing the interest rate, you can nod knowingly and say, "Ah, they're just trying to keep the economy dancing to the right beat."
And who knows, maybe one day, the Bank of England will decide to swap the sweet jar for a piñata. Now wouldn't that be a party?
