
How Much Will Insurance Cost
Ever wondered what it's like to have a conversation with your insurance agent? It's a bit like trying to understand a toddler who's just discovered the joy of telling knock-kn...

Ever wondered what it's like to have a conversation with your insurance agent? It's a bit like trying to understand a toddler who's just discovered the joy of telling knock-knock jokes. You know, the ones where they laugh at their own punchline, and you're left scratching your head, wondering if you missed something? That's kind of what insurance jargon feels like. But don't worry, we're going to demystify the cost of insurance, one funny comparison at a time.
So, What's the Deal with Insurance Costs?
Imagine insurance costs are like a pizza. You know, the kind you order when you've had a long week and all you want is a cheesy, greasy slice of heaven. Now, you could go for the plain cheese, but where's the fun in that? You want the works - pepperoni, mushrooms, olives, the whole shebang. That's where insurance add-ons come in. They're like those extra toppings that make your pizza (or your insurance) a bit more expensive, but oh-so-worth-it.
Factor #1: The Base - Your Deductible
Your deductible is like the pizza base. It's the amount you pay out of pocket before your insurance kicks in. Think of it as the crust - it's not the most exciting part, but it's necessary. The higher your deductible, the more you pay upfront, but the lower your monthly premium. It's like choosing a thicker crust - it might cost a bit more, but it's more substantial, you know?
Must Read
Factor #2: The Toppings - Coverage Limits
Coverage limits are like those extra toppings. You can choose how much you want, but each topping comes with a price. The more coverage you want, the more you'll pay. It's like ordering extra pepperoni - it's delicious, but it's going to cost you a bit more. But remember, you don't want to skimp on the toppings (or coverage) and end up with a bland pizza (or an underinsured situation).
Factor #3: The Sauce - Your Location
Where you live can affect your insurance costs, just like where you order your pizza from can affect the price. If you live in an area with a high crime rate or a history of natural disasters, your insurance is going to cost more, just like a pizza from a fancy pizzeria in a trendy neighborhood is going to cost more than one from your local joint.
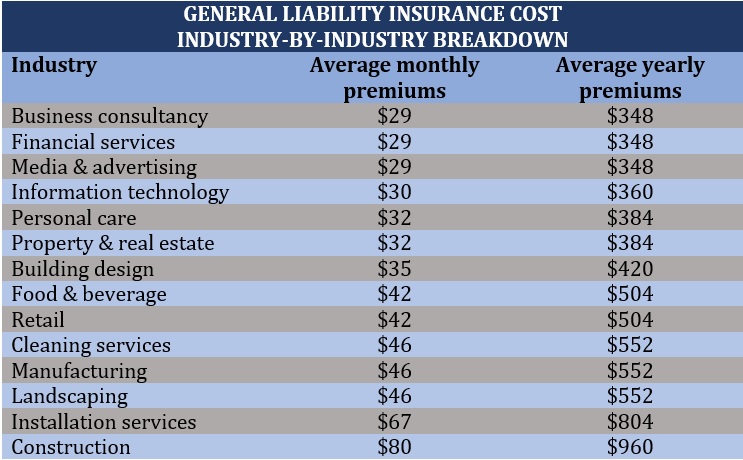 How much does general liability insurance cost? (2026)
Factor #4: The Cheese - Your Insurance Score
Your insurance score is like the cheese on your pizza. It's not the most important part, but it can make a big difference in the taste (or cost) of your insurance. The better your score, the less you'll pay. It's like choosing a fancy, artisanal cheese - it's going to cost more, but it's going to make your pizza (or your insurance) taste a whole lot better.
But How Much Are We Talking Here?
Alright, let's get down to brass tacks. How much is this insurance pizza going to cost you? Well, it depends. On average, Americans spend about $1,600 a year on insurance. But remember, that's just the average. Your cost could be more or less, depending on your pizza (or insurance) preferences.
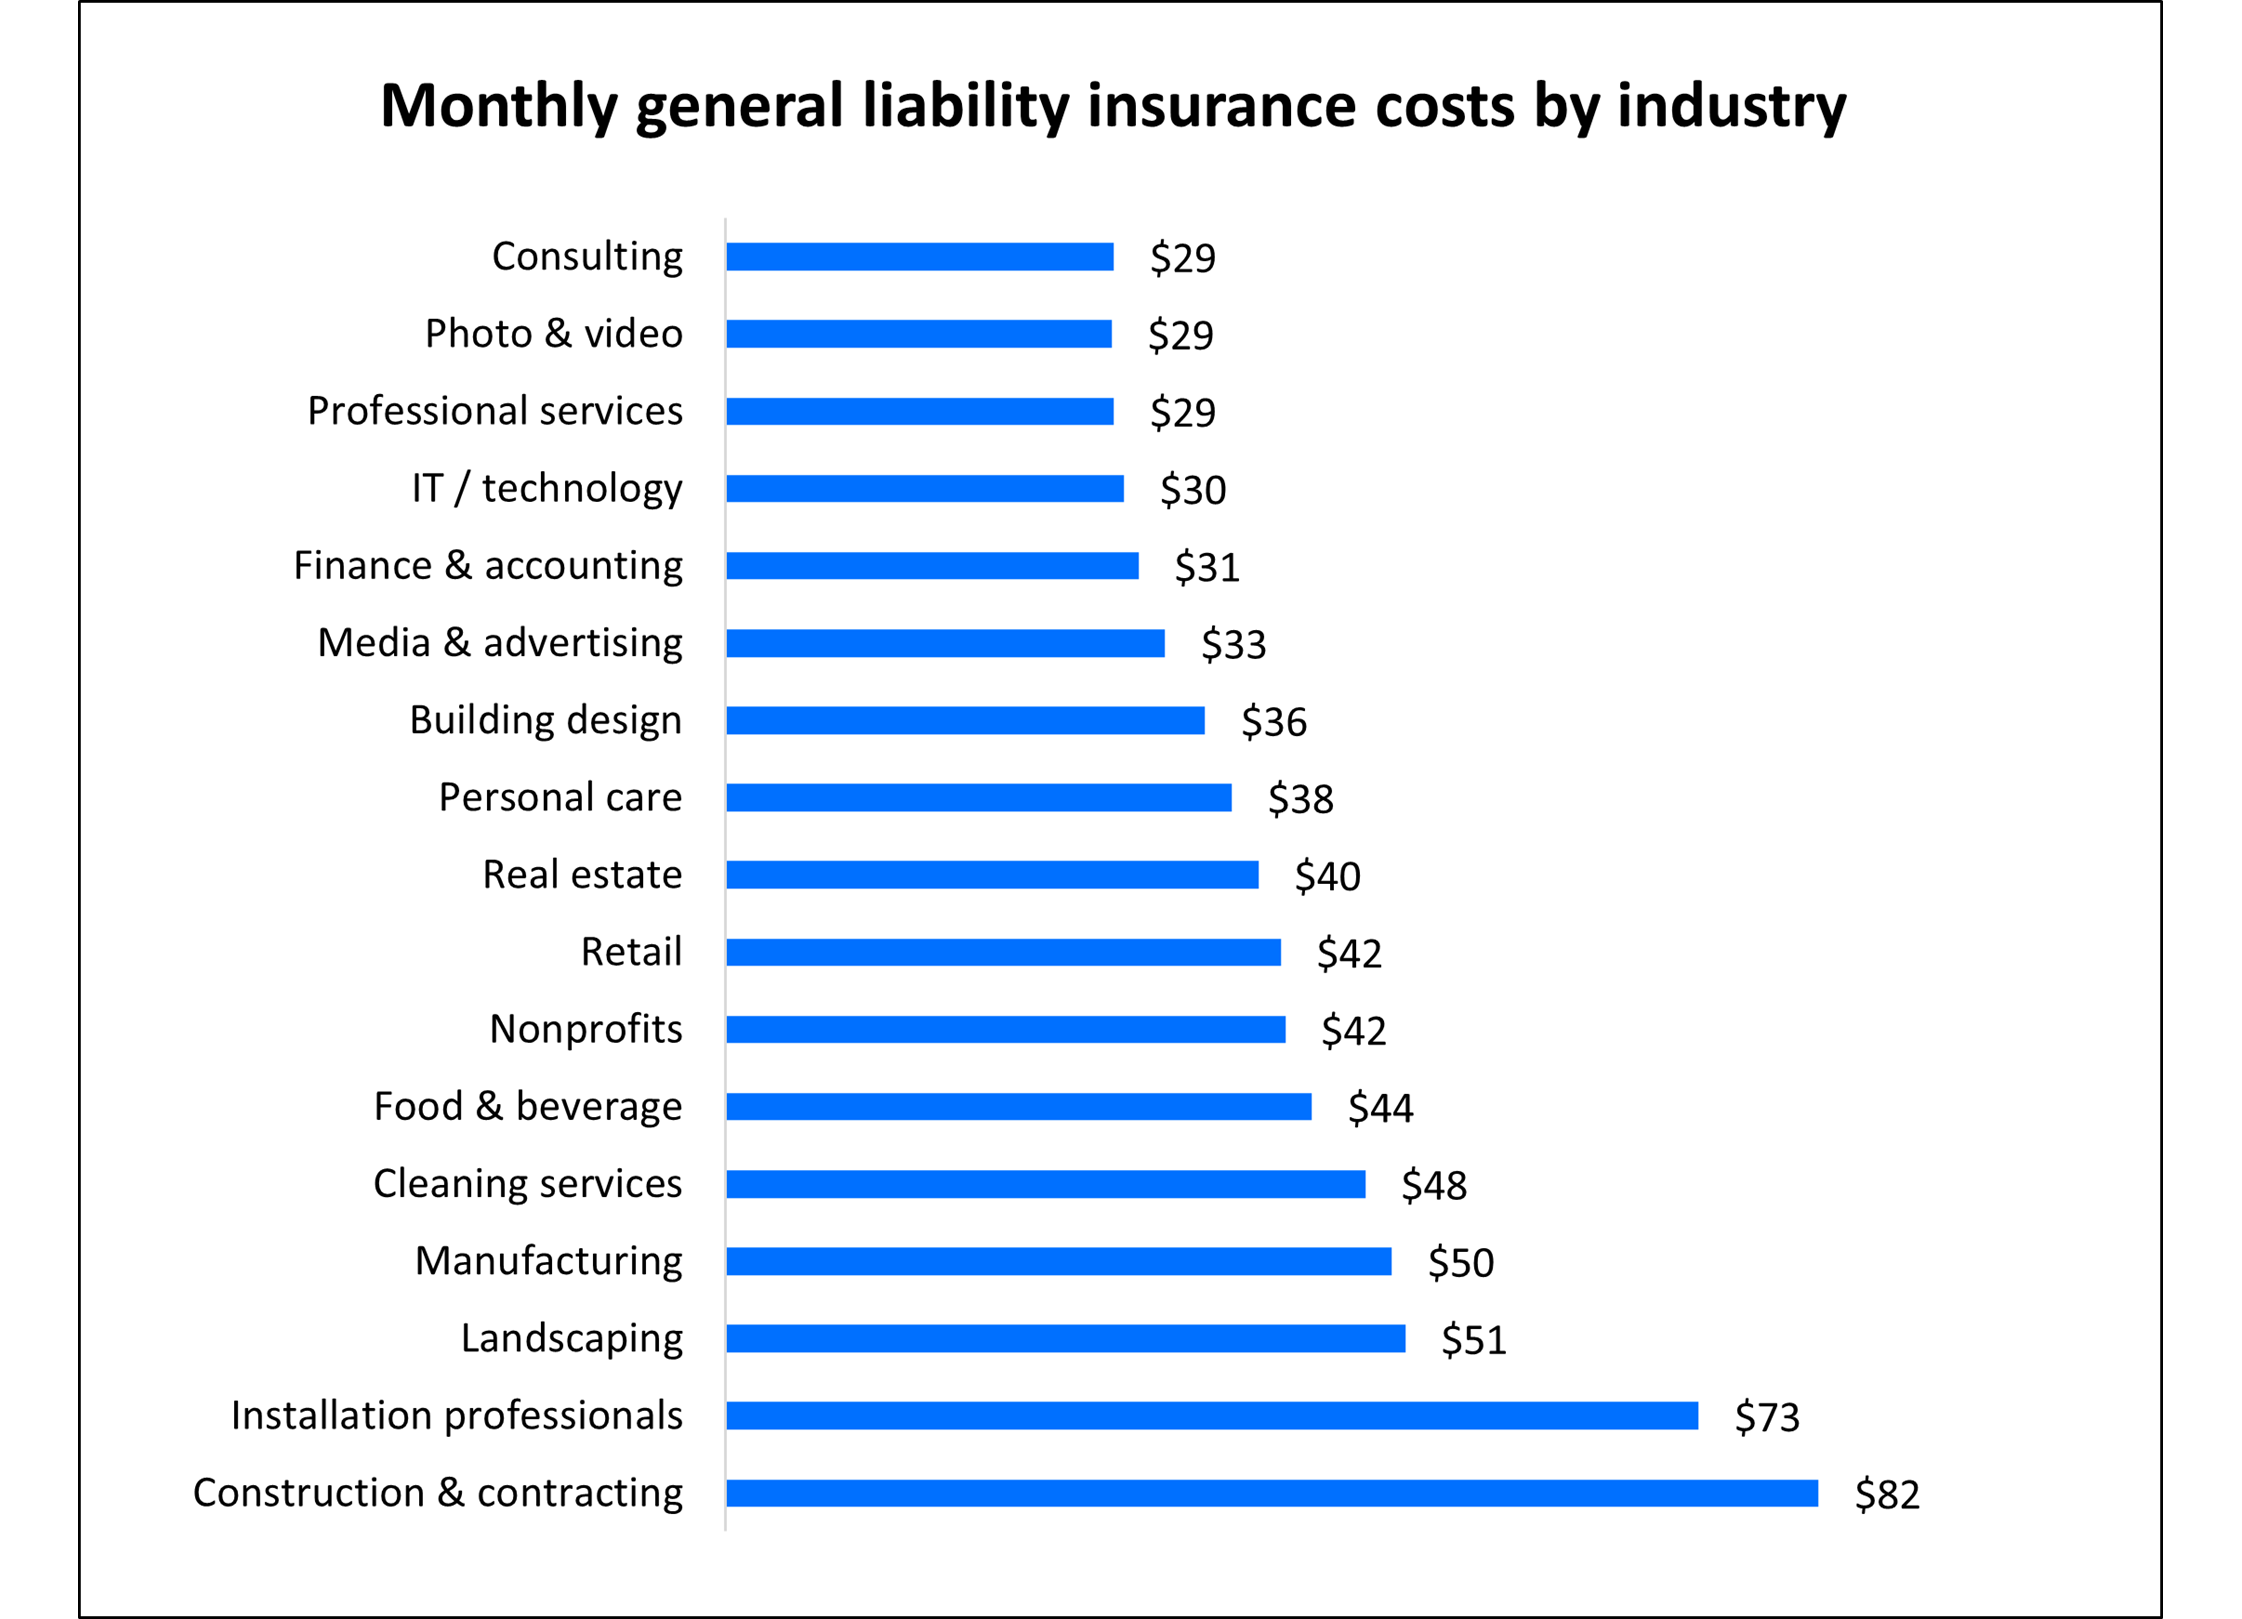 Product Liability Insurance Cost: Fast & Free Quotes | Insureon
Now, I know what you're thinking. "That's a lot of money for a pizza!" Well, yes, it is. But remember, insurance isn't just about protecting your stuff - it's about protecting your peace of mind. It's like ordering that pizza after a long week. Sure, it's a bit of an investment, but it's worth it in the end.
So, there you have it. Insurance costs, explained in the most delicious way possible. Next time you're wondering why your insurance is costing you an arm and a leg, just remember - it's like ordering a pizza with all the toppings. It's going to cost you, but it's going to be worth it.
