
How To Get A Large Mortgage
So, You Wanna Score a Big Mortgage, Eh? Alright, gather 'round, folks. We're about to dive into the world of mortgages, and I promise, it won't be as boring as watching paint...
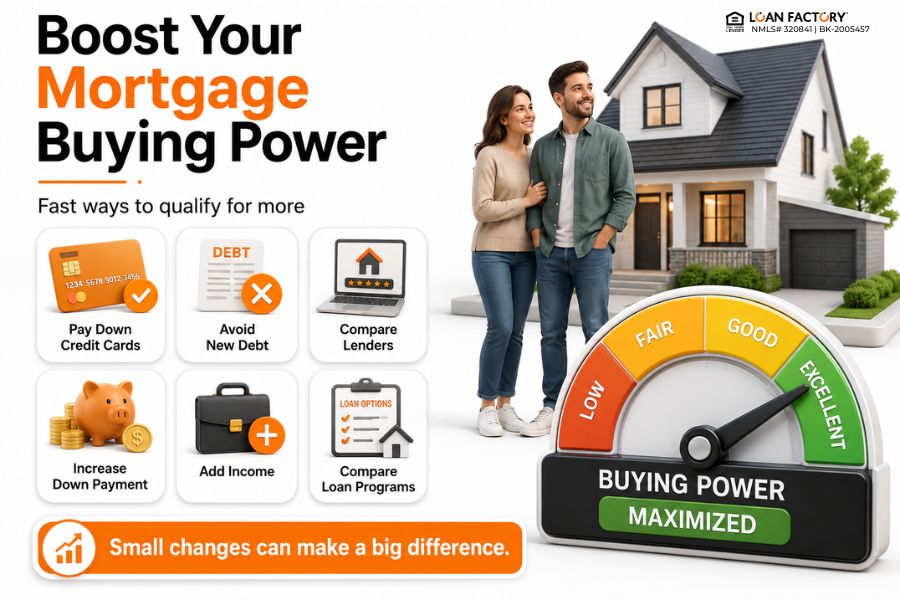
So, You Wanna Score a Big Mortgage, Eh?
Alright, gather 'round, folks. We're about to dive into the world of mortgages, and I promise, it won't be as boring as watching paint dry. In fact, let's think of this as a game of poker. You're at the table, you've got your chips, and you're aiming for that big pot. The mortgage, in this case, is the jackpot you're after.
First Things First: Check Your Credit Score
Before you even think about sitting at that poker table, you need to know what you're working with. Your credit score is like your stack of chips - it's what you'll be betting with. So, pull out your trusty credit card (not literally, that's a fire hazard), and check your score. If it's shiny and high, great! You're ready to play. If it's a bit... lacking, don't worry, we'll get to that.
Save, Save, Save: The Art of Stacking Chips
Now, you might be thinking, "I've got a decent credit score, but I'm not exactly rolling in dough." Well, friend, it's time to start saving. Think of it like this: every time you skip that fancy coffee, you're not just saving money, you're building your mortgage army. Every dollar saved is a soldier ready to fight for your dream home. And who knows, maybe one day you'll look back and realize you've been brewing your own coffee all along. (Gasp! The horror!)
Must Read
Now, Let's Talk Strategy
You've got your credit score, you've been saving like a pro. Now it's time to figure out how much you can actually afford. This is where things get real. It's like you're at the poker table, and you've got to decide how much to bet. You don't want to go all in and end up broke, but you don't want to bet too little and miss out on that sweet, sweet jackpot.
Debt-to-Income Ratio: Your Poker Face
Here's where we introduce the debt-to-income ratio, or DTI. It's like your poker face - it tells the lender whether you're bluffing or if you're the real deal. Lenders typically want your DTI to be 43% or less. That means your total debt payments (including your new mortgage) should be 43% or less of your gross monthly income. So, if you make $5,000 a month, your total debt payments should be $2,150 or less. Easy peasy, right?
 3 Tips for Getting a Larger Mortgage When Buying a House - YouTube
Loan-to-Value Ratio: The Big Bet
Next up, we've got the loan-to-value ratio, or LTV. This is like your big bet at the poker table. It's the size of your loan compared to the value of the home. Lenders typically like to see an LTV of 80% or less. So, if you're buying a home worth $300,000, you'd need to put down at least $60,000 to keep your LTV at 80% or less. That's a big bet, but it's a smart one. It shows the lender you're serious, and it can help you avoid private mortgage insurance (PMI), which is like an extra tax you don't want to pay.
Now, Let's Talk Tactics
You've got your credit score, you've saved up, you've figured out what you can afford. Now it's time to talk tactics. You're at the poker table, and you're ready to make your move. But wait, there's more to this game than just betting big.
Shop Around: Find the Best Interest Rate
Interest rates are like the house's edge in this game. They can make or break your mortgage. So, don't just go with the first lender you find. Shop around. Compare interest rates. Remember, a lower interest rate means you'll pay less over time. It's like finding a way to make the house pay you instead of the other way around. (Now that's a trick worth learning!)
 Unlocking Your Dream Home: 10 Tips for a Large Mortgage - YouTube
Consider an FHA Loan: The Wild Card
Alright, here's a wild card for you: FHA loans. They're like that mysterious player at the poker table who always seems to win. FHA loans are government-backed mortgages designed for low-to-moderate income borrowers. They require a lower down payment (as little as 3.5%) and have more flexible credit score requirements. They can be a lifesaver if you're struggling to save for a down payment or if your credit score is less than stellar.
Final Thoughts: The Big Win
So, there you have it. You've checked your credit score, you've saved up, you've figured out what you can afford, and you've got your tactics ready. You're sitting at that poker table, and you're ready to win that big mortgage. But remember, this isn't a game of chance. It's a game of strategy. It's about knowing your limits, playing smart, and making the right bets.
And hey, if all else fails, there's always that fancy coffee you've been missing. You can always treat yourself to that after you've won that big mortgage. Just don't make a habit of it. After all, every dollar counts when you're building your mortgage army.
