
What Is Credit Card Interest
So, you're here because you're curious about credit card interest, huh? Well, buckle up, buttercup, 'cause we're about to dive into a world of numbers that dance like there's...

So, you're here because you're curious about credit card interest, huh? Well, buckle up, buttercup, 'cause we're about to dive into a world of numbers that dance like there's no tomorrow. Grab a coffee, make yourself comfy, and let's get this show on the road.
What's the Deal with Interest, Anyway?
Alright, imagine you're at a fancy dinner party, and you've just ordered a dish that costs, let's say, a cool $100. But instead of paying upfront, you decide to put it on your credit card. Now, the bank is like, "Sure thing, buddy! But hey, you know what? We're gonna tack on a little extra for the privilege. You cool with that?" And that, my friend, is interest in a nutshell.
But wait, there's more! It's not just about the initial purchase. Interest is like that annoying party guest who just won't leave. It keeps hanging around, growing, and multiplying like a certain someone's holiday weight gain. And just like that, your $100 dinner turns into a $150 bill. Ouch!
Must Read
How Much We Talking Here?
Now, you might be thinking, "That's all well and good, but how much are we talking about?" Well, that depends on your credit card's interest rate. Most cards have an Annual Percentage Rate (APR) that can range from around 12% to a whopping 25% or more. That's like finding out your favorite restaurant just jacked up their prices by 25% - not cool!
But here's where it gets interesting (pun intended). Some cards have different interest rates for different types of transactions. For instance, purchases might have one rate, while cash advances have another. It's like having two different menus at that fancy dinner party - one for the good stuff, and one for the stuff that'll cost you an arm and a leg.
So, How Does It Work?
Alright, so you've got your interest rate, and you've made a purchase. Now what? Well, every month, your credit card company calculates the interest you owe based on your average daily balance. It's like they're adding up all the tabs at the dinner party and dividing it by the number of days in the month. Then, they multiply that by your interest rate. Voila! Interest calculated.
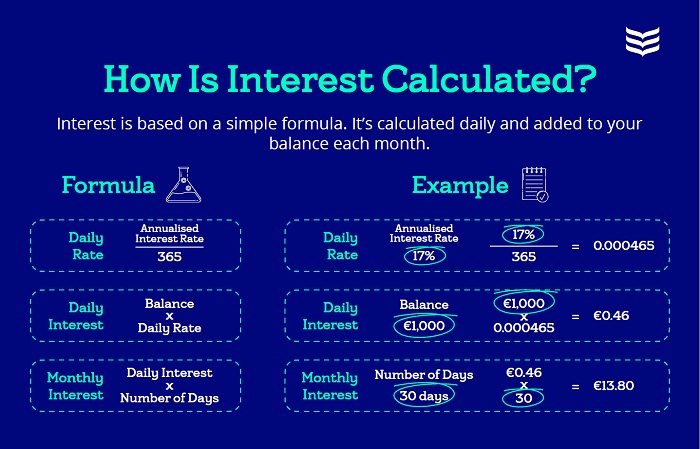 Understanding credit card interest - Bank of Ireland
But here's the kicker - if you pay off your balance in full every month, you won't have to pay any interest at all. It's like they never even calculated it in the first place. Magic, right?
But Wait, There's More!
You thought we were done? Oh, no, no, no. We've barely scratched the surface. There are different types of interest calculations, too. Some cards use a daily periodic rate, while others use a monthly periodic rate. It's like they're speaking a different language just to confuse you. But don't worry, as long as you understand the basics, you'll be just fine.
And then there are grace periods. Some cards give you a little break and don't charge interest if you pay off your balance within a certain time frame. It's like they're giving you a free pass to the dessert bar - but only if you promise to behave.
 5 Easy Ways to Calculate Credit Card Interest - wikiHow
The Moral of the Story
So, what have we learned today, kids? Well, credit card interest is like that annoying party guest who just won't leave. It sneaks up on you, multiplies like a certain someone's holiday weight gain, and can leave you with a hefty bill if you're not careful. But if you're smart, pay off your balance in full every month, and keep an eye on those interest rates, you'll be just fine.
And remember, folks, credit cards aren't the enemy. They're just a tool. Use them wisely, and they'll serve you well. But use them recklessly, and they'll leave you with a hangover that'll last longer than that fancy dinner party.
So, go forth, my friends, and use your credit cards responsibly. And next time you're at a dinner party, remember to tip your waiter generously. Trust me, it's worth it.
