What Is Credit Score Out Of
Ever wondered what that three-digit number is that seems to hold so much power over our financial lives? You know, the one that lenders, landlords, and even some employers see...
Ever wondered what that three-digit number is that seems to hold so much power over our financial lives? You know, the one that lenders, landlords, and even some employers seem to be obsessed with? Yeah, that's your credit score, and it's way cooler than you might think.
So, What's the Deal with This Magic Number?
Your credit score is like your financial report card. It's a snapshot of how responsible you've been with credit in the past, and it helps lenders decide if you're a safe bet for future loans. But here's the thing: it's not some mysterious, untouchable number. It's calculated based on a bunch of factors, and it can change over time. Kind of like your GPA in school, but with way more real-world consequences.
What's in a Score?
Your credit score is made up of five main factors. It's like a recipe, and each ingredient plays a role in the final dish. The first and biggest chunk is your payment history - that's 35% of your score. It's like your attendance record in school; if you've been consistently showing up and paying your bills on time, you're off to a great start.
The next biggest factor is the amount you owe, which makes up 30% of your score. This is like your workload - the more you've got on your plate, the more it can affect your performance. In this case, the more debt you have, the more it can drag down your score. But don't worry, it's not just about the total amount. It's also about how much you owe compared to your credit limits - that's your credit utilization ratio.
The remaining 35% is a mix of new credit (10%), the types of credit you have (10%), and the length of your credit history (15%). It's like the extracurricular activities, recommendations, and GPA boosters that can give you that extra edge. Having a mix of credit types, like credit cards and installment loans, can show lenders that you're versatile. And the longer your credit history, the more they can see your track record.
Why Should You Care?
Your credit score is like your financial superpower. It can unlock all sorts of cool stuff, like low-interest rates on loans, better credit card rewards, and even lower insurance premiums. It's like leveling up in a video game - the higher your score, the more perks you get.
 Credit scores explained: A guide to understanding your credit score
But here's the thing: it's not just about what you can get. It's also about what you can protect. A good credit score can help you avoid security deposits on utilities, better apartment options, and even better job opportunities. It's like having a shield that protects you from financial pitfalls.
Can You Change Your Score?
You might be thinking, "This all sounds great, but what if my credit score is more like a participation trophy right now?" Don't worry, it's not set in stone. Your credit score is always changing, and that means you can always improve it. It's like training for a marathon - it takes time and effort, but with each step, you're getting stronger.
Here's the secret sauce: pay your bills on time, keep your credit utilization low, and don't apply for too many new credit accounts at once. It's like a financial diet - it might not be the most exciting thing in the world, but it's what you need to reach your goals.
 Credit Rating Pie Chart at Dorla Walker blog
So, What's a Good Score?
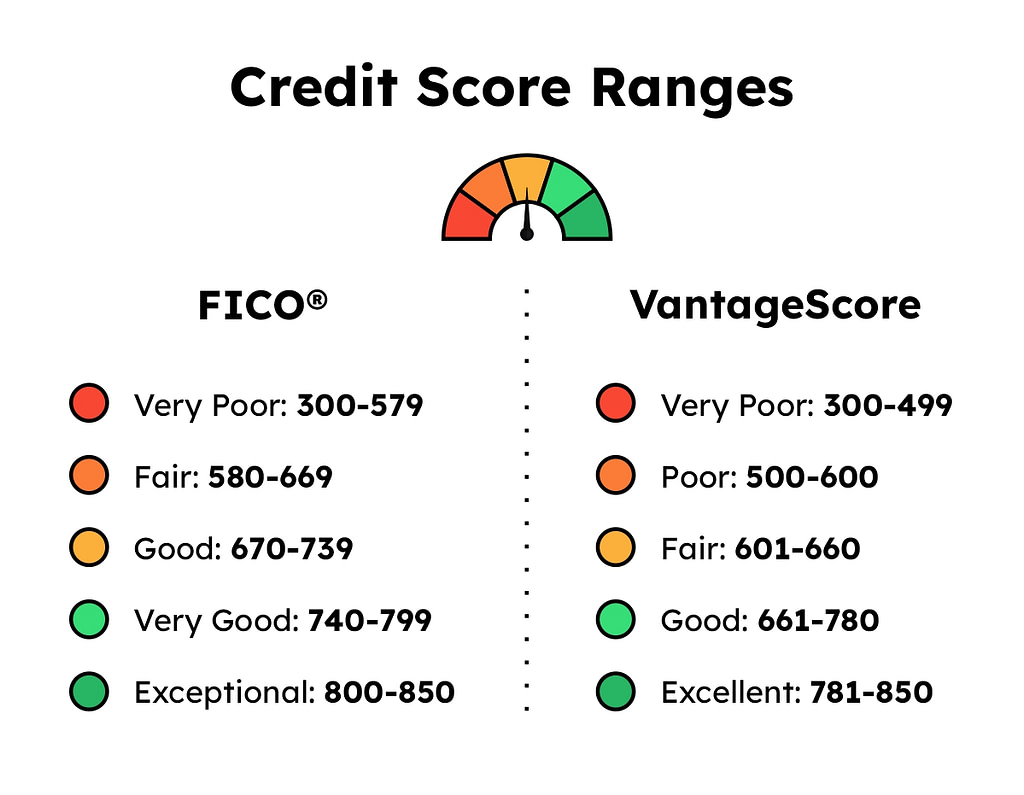
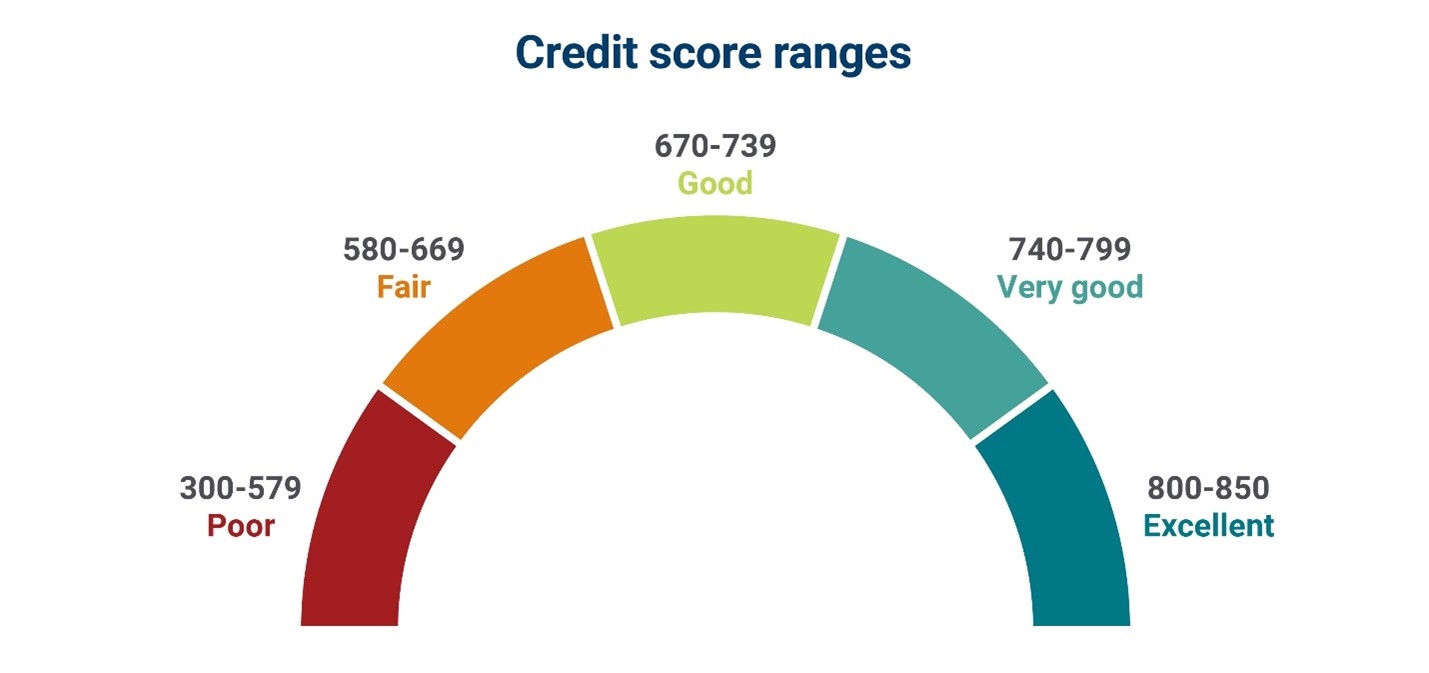
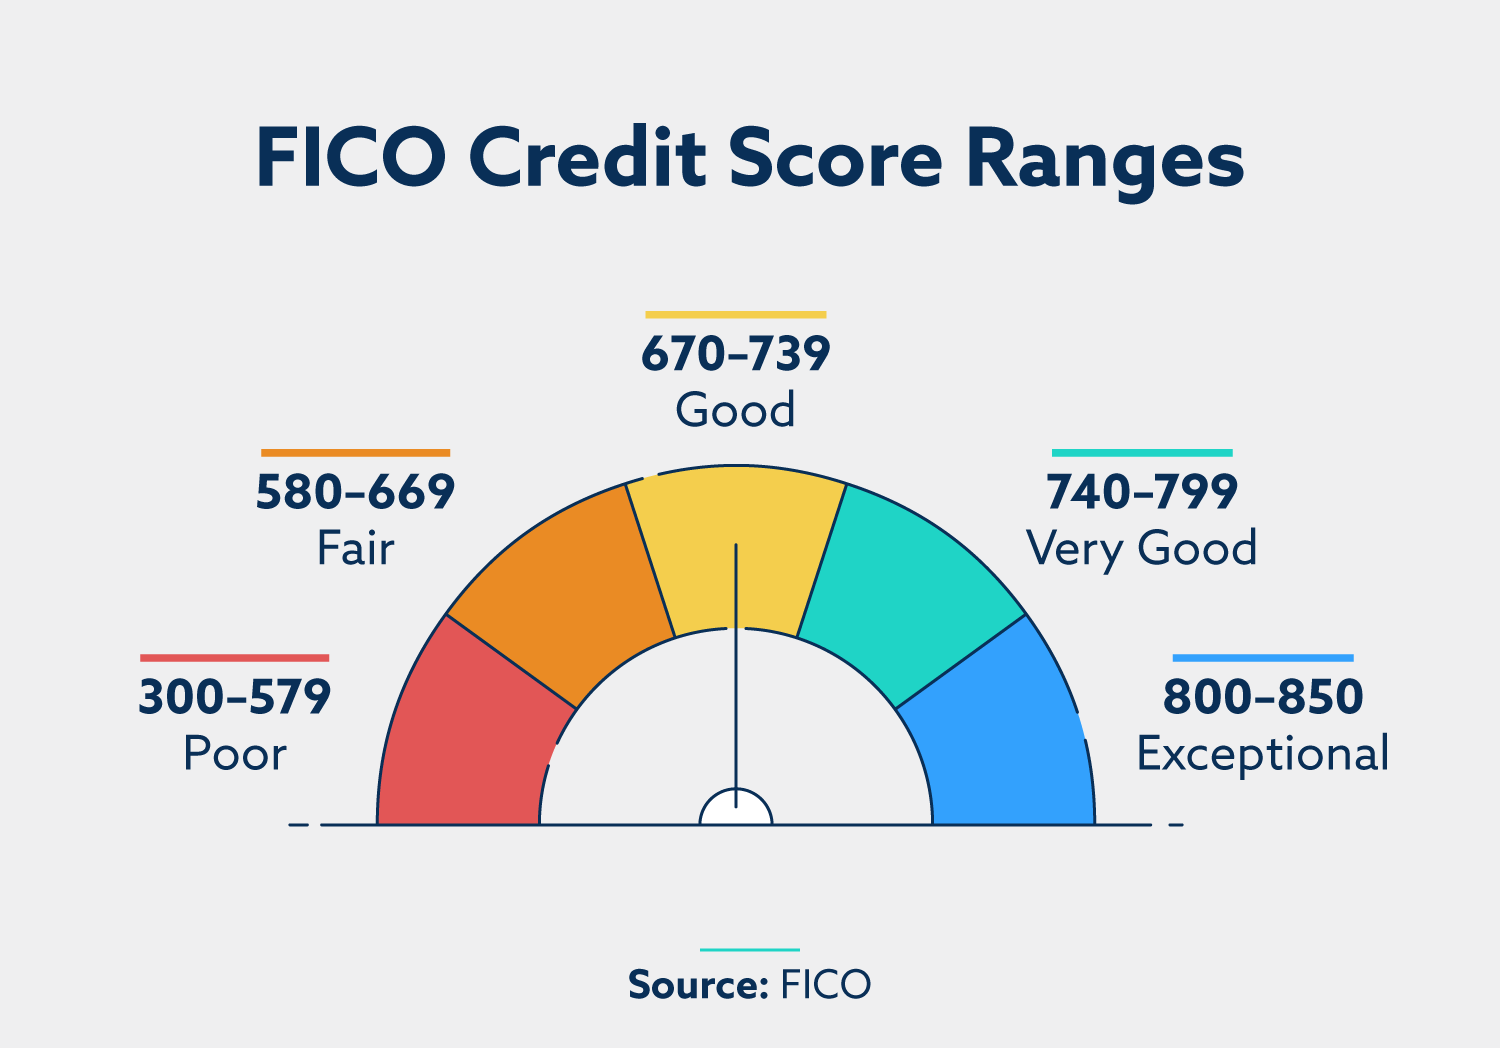
You might be wondering, "Okay, I get it. I need a good credit score. But what does 'good' even mean?" Good question! The most common credit scoring model, FICO, ranges from 300 to 850. Here's a quick breakdown:
- Exceptional: 800-850. You're in the top 20% of scorers. You're basically the valedictorian of credit.
- Very Good: 740-799. You're in the top 10%. You're like the student council president.
- Good: 670-739. You're right in the middle. You're passing, but there's still room for improvement.
- Fair: 580-669. You're in the bottom 40%. You're not failing, but you're not acing it either.
- Very Poor: 300-579. You're in the bottom 10%. You're basically the kid who forgot to turn in their homework all year.
Remember, these are just guidelines. Lenders can have their own standards, and some might be more lenient than others. But if you're aiming for 'exceptional,' you're on the right track.
Final Thoughts
Your credit score is a lot more interesting than it seems at first glance. It's a snapshot of your financial journey, and it's always changing. It's like your financial fingerprint - unique, always evolving, and packed with potential. So, go ahead, take a look at your score. See where you stand. And then start thinking about where you want to go. Because your financial future is in your hands, and it's way cooler than you might think.
