Calculate Yield To Maturity Formula
Hey there, finance enthusiast! Grab a coffee, pull up a chair, and let's chat about this nifty little thing called the Yield to Maturity (YTM) formula. You know, that magical...
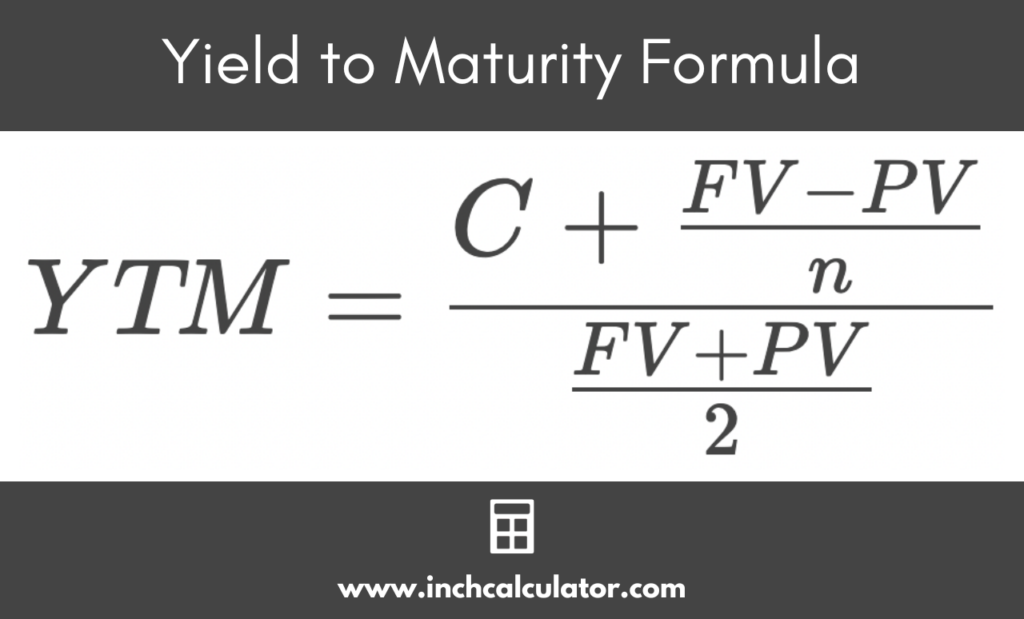
Hey there, finance enthusiast! Grab a coffee, pull up a chair, and let's chat about this nifty little thing called the Yield to Maturity (YTM) formula. You know, that magical equation that helps us figure out the average return an investor gets from a bond, assuming it's held until it matures.
Now, you might be thinking, "Why do I need to know this? I'm just here for the lattes." Well, friend, understanding YTM can help you make smarter investment decisions. It's like having a secret decoder ring for the bond market.
So, what's this formula all about?
Alright, let's dive in. The YTM formula is pretty straightforward. It's like a recipe, with just a few ingredients:
- C: The bond's current market price.
- FV: The bond's face value (or par value).
- r: The bond's annual coupon rate.
- n: The number of times the bond pays interest per year.
- t: The time until the bond matures, in years.
And here's the formula: YTM = [(C + (FV - C) * (1 - (1 + r/n)^-nt)) / (FV + (FV - C) * (1 - (1 + r/n)^-nt))] * (1 + r/n)
I know, I know, it looks like a mouthful. But don't worry, we'll break it down together.
Let's start with the basics: C and FV
Imagine you're at the coffee shop, and you see a bond on the menu. The C is like the price you see on the board - it's what the bond is currently worth in the market. The FV, on the other hand, is like the price you'd pay if you bought the bond directly from the issuer. It's the bond's face value, or what it's worth if you hold it until it matures.
Now, let's say you're looking at a bond that has a face value of $1,000 (FV = $1,000), but it's currently trading at $950 (C = $950). That means you could buy it for a discount, right?
Next up: r and n
Now, let's talk about the bond's interest rate, r. This is like the barista's tip - it's a percentage of the bond's face value that the issuer pays you each year. For example, if the bond has an annual coupon rate of 5% (r = 5%), the issuer will pay you $50 each year ($1,000 * 0.05 = $50).
But wait, there's more! We also need to know how often the bond pays interest. Is it once a year, twice a year, or even more frequently? That's our n - the number of times the bond pays interest per year. If the bond pays interest twice a year, then n = 2.
Last but not least: t
Finally, we need to know how long until the bond matures, or t. This is like the time it takes for your coffee to brew. If the bond matures in 5 years, then t = 5.
 Bond Discount | Definition, Factors, Calculation, Risks, Strategies
Now that we've got all our ingredients, let's plug them into the formula. Don't worry, you don't have to do the math by hand. There are plenty of online calculators that can do the heavy lifting for you.
Why should you care about YTM?
Alright, so you've calculated the YTM. Now what? Well, knowing the YTM can help you compare different bonds and make smarter investment decisions. It's like knowing the difference between a regular coffee and a fancy, overpriced latte - you can decide which one is worth your money.
For example, let's say you're looking at two bonds. One has a higher YTM but also comes with more risk. The other has a lower YTM but is considered safer. With the YTM in hand, you can decide which bond is the better deal for you, given your risk tolerance.
Plus, understanding YTM can help you figure out when it's a good time to sell a bond. If the YTM drops below the bond's coupon rate, it might be time to cash out and find a better deal elsewhere.
So, are you ready to become a YTM pro?
I know, I know, it can seem intimidating at first. But with a little practice, you'll be whipping up YTM calculations like a barista makes lattes. And who knows, you might even start to enjoy the process.
Remember, the key to understanding YTM is to keep practicing and asking questions. Don't be afraid to grab another coffee and dive back in. After all, the more you know about YTM, the better equipped you'll be to navigate the bond market.
Now, who's ready for a refill? Let's keep the conversation going!
