How Rate Of Interest Is Calculated
Ever wondered how banks decide how much interest to charge you on your credit card balance, or how much they'll pay you for keeping your money in a savings account? It's all a...

Ever wondered how banks decide how much interest to charge you on your credit card balance, or how much they'll pay you for keeping your money in a savings account? It's all about the rate of interest, and it's not as mysterious as it might seem. Let's dive in, shall we?
Simple Interest: The OG of Interest Rates
Imagine you're at a music festival, and you've just bought a $100 t-shirt. But wait, the vendor says you can pay in installments! If you pay $20 now and $20 every month for the next four months, you're essentially paying simple interest. The total amount you'll pay is $140 - $100 for the t-shirt and $40 in interest.
The formula for simple interest is: I = P * r * t, where I is the interest, P is the principal (the initial amount), r is the rate of interest per period, and t is the time in years. In our t-shirt example, P is $100, r is 20% per year (since you're paying $20 every month, which is 20% of $100), and t is 0.33 years (4 months).
Must Read
Compound Interest: The Party Trick of Interest Rates
Now, let's say you're at the same festival, but this time, you've brought your friend who's a financial whiz. They tell you about compound interest. Instead of paying interest only on the initial $100, you'd pay interest on the growing balance. So, you'd pay $20 the first month, but the next month, you'd owe interest on $120, then $140, and so on.
The formula for compound interest is a bit trickier: A = P * (1 + r/n)^(nt), where A is the amount after time t, P is the principal, r is the annual interest rate, n is the number of times that interest is compounded per year, and t is the time the money is invested or borrowed for, in years.
See, compound interest is like a party trick because it grows exponentially. It's why investing early is so important - your money has more time to grow. It's also why credit card debt can spiral out of control if you don't pay off your balance each month.
APR: The Interest Rate You'll Actually See
When you're looking at interest rates, you'll often see Annual Percentage Rate (APR). This is the interest rate you'll pay on a yearly basis. It's important because it helps you compare different loans or credit cards.
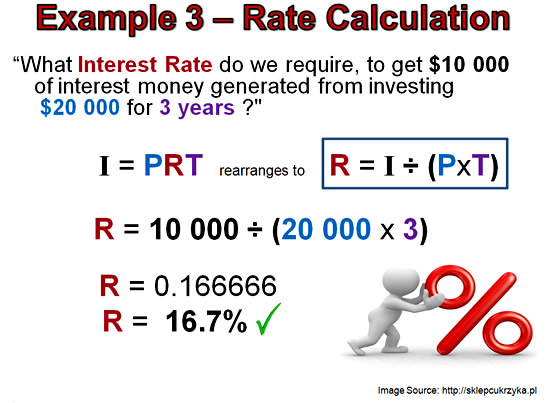 Simple Interest – Part One | Passy's World of Mathematics
For example, let's say you're looking at two credit cards. One has an APR of 15%, and the other has an APR of 18%. If you have a $10,000 balance, you'd pay $1,500 in interest on the first card and $1,800 on the second. That's a difference of $300!
Interest Rates in Pop Culture
Interest rates have even made their way into pop culture. Remember the movie The Big Short? It's all about the 2008 financial crisis, and interest rates play a big part. And who could forget the song "Money Trees" by Kendrick Lamar? The lyrics "I need a money tree, I need a money tree" might not be about interest rates, but they're certainly about the power of money growing over time.
Interest Rates in Daily Life
So, how does all this apply to your daily life? Well, understanding interest rates can help you make better financial decisions. It can help you choose the right credit card, the best savings account, or the most affordable loan. It can also help you understand why it's so important to pay off your credit card balance each month.
Think of interest rates like the weather. You might not be able to control them, but knowing how they work can help you plan and prepare. So, the next time you're at the bank or considering a loan, you'll know exactly what you're getting into. And isn't that a refreshing feeling?
