What Happens To Someone's Pension When They Die
So, You're Wondering What Happens to Your Pension When You Kick the Bucket? Alright, let's dive into this, shall we? Imagine your pension as a big, cozy nest egg you've been...
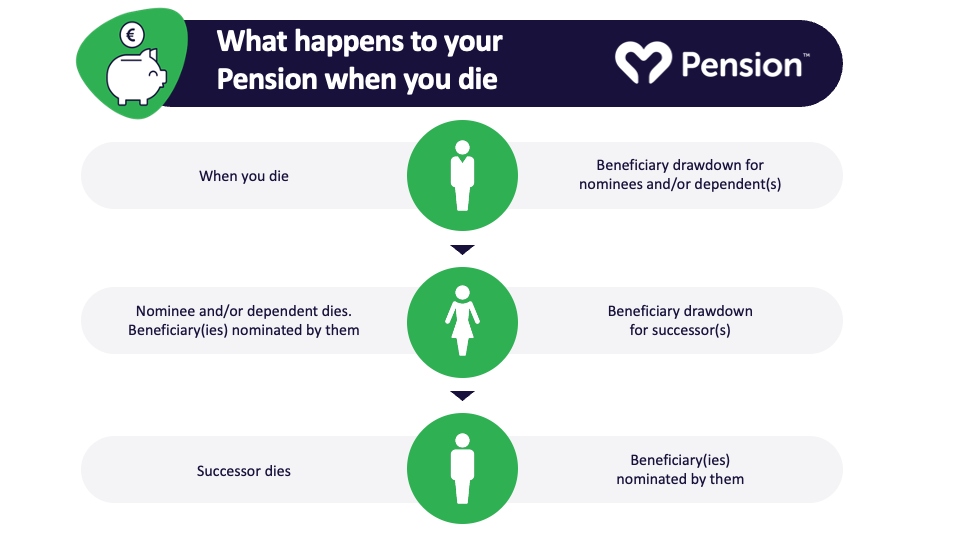
So, You're Wondering What Happens to Your Pension When You Kick the Bucket?
Alright, let's dive into this, shall we? Imagine your pension as a big, cozy nest egg you've been hatching all your life. You've been feeding it with those monthly contributions, and now it's ready to hatch into a beautiful retirement. But what if you don't get to enjoy your golden years with it? Well, that's what we're here to chat about.
First Things First: It's Not Like in the Movies
You know those movies where someone dies, and their fortune is magically split among their heirs in a matter of days? Yeah, that's not how it works in real life. Pensions, especially defined benefit plans, are a bit more complex. They're not just a big chunk of cash waiting to be claimed.
Think of it like a promise. Your employer, or the government, has promised you a certain amount of money each month when you retire. That promise is backed by investments and sometimes even guarantees. So, when you die, that promise doesn't just disappear. It's like a contract that needs to be honored, one way or another.
Must Read
What Happens to That Promise When You're Gone?
Well, it depends on the type of pension you have and what you've planned for. Let's break it down:
Defined Benefit Pensions
These are the old-school pensions where your employer promises you a certain amount of money each month in retirement. When you die, that promise doesn't just vanish. It usually gets passed on to your surviving spouse or beneficiary, depending on what you've chosen.
It's like when you order a big, juicy steak at a restaurant, but you can't finish it. You can't take it home, but you can ask the waiter to wrap it up for your friend. That's what happens with a defined benefit pension. The 'steak' (your pension) gets passed on to someone else.
Defined Contribution Pensions
These are the pensions where you and your employer contribute to an investment account. When you die, the money in that account doesn't just disappear. It gets passed on to your beneficiary, just like with a 401(k) or an IRA.
Think of it like a piggy bank. You've been filling it up with coins (your contributions) all your life. When you die, your kid gets to smash the piggy bank open and spend all those coins. That's what happens with defined contribution pensions.
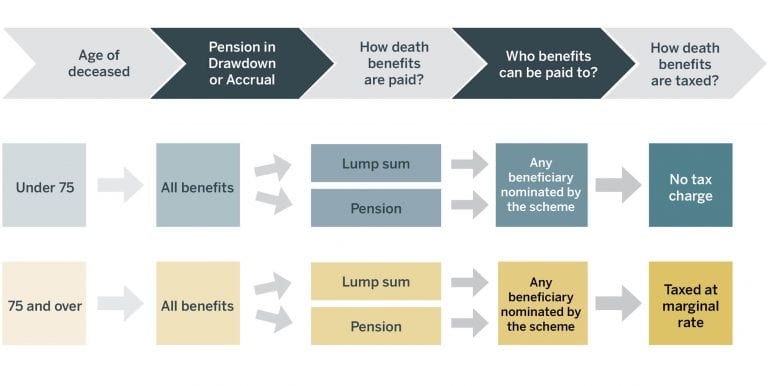 What happens to my pension on death? - fmifa
But What If You Haven't Planned Anything?
Well, that's where things can get a bit tricky. If you haven't chosen a beneficiary, or if your beneficiary has also passed away, the money might go into probate. That's like a big, messy estate sale where the court decides who gets what.
To avoid this, it's always a good idea to have a will and to keep your beneficiary designations up to date. It's like making sure you've got a clear map for your nest egg. You don't want it to get lost in the shuffle after you're gone.
Taxes, Taxes, Taxes
Death and taxes, right? Even after you're gone, your pension might still have to pay Uncle Sam a visit. The rules can get a bit complicated, so it's always a good idea to talk to a financial advisor or a tax professional.
Think of it like a final exam. You've studied hard (planned your pension), but you still need a tutor (a professional) to help you ace it (minimize taxes).
So, What's the Moral of the Story?
Pensions are like promises. They don't just disappear when you die. They need to be honored, one way or another. So, it's important to plan for what happens to that promise when you're gone. It's like making sure your nest egg has a safe place to land, even if you're not around to enjoy it.
And remember, it's never too early to start planning. You don't want to leave your loved ones with a big, confusing mess to clean up. So, grab a pen, pour yourself a cup of coffee, and let's get planning!
