What Happens To Your Private Pension When You Die Gov
So, You've Been Wondering What Happens to Your Private Pension When You Kick the Bucket, Eh? Picture this: You're sitting in your favorite armchair, sipping on your well-dese...
So, You've Been Wondering What Happens to Your Private Pension When You Kick the Bucket, Eh?
Picture this: You're sitting in your favorite armchair, sipping on your well-deserved retirement tea, when suddenly, you remember that little nest egg you've been building for years. You've been wondering, "What happens to my private pension when I die?" It's a fair question, mate, and I'm here to shed some light on it.
First Things First: It's Not as Scary as It Sounds
I know, I know, talking about death isn't exactly the most cheerful topic, but bear with me. The good news is, your private pension doesn't just vanish into thin air when you're gone. It's there to take care of your loved ones, or even yourself, if you've planned for some fancy late-life adventures.
Meet the Beneficiaries: Your Pension's New Best Friends
When you set up your pension, you probably named someone - or a few someones - as your beneficiary. These are the lucky folks who'll inherit your pension pot when you're no longer around to enjoy it yourself. If you haven't named any beneficiaries, don't worry, we'll get to that too.
Must Read
Now, here's where things get a tad more complicated. The way your pension gets passed on depends on the type of pension you have. Let's dive into the two most common types:
Defined Contribution Pensions: The Wildcard
If you've got a defined contribution pension, like a personal pension or a workplace pension, then your beneficiary will get a lump sum. Simple, right? Well, not quite. The amount they get depends on a few factors:
- Your Age: If you're under 75 when you die, your beneficiary will get the full lump sum, tax-free. If you're over 75, they'll pay inheritance tax on the amount above the tax-free allowance (currently £325,000).
- Your Pension Pot: If your pension pot is worth more than the tax-free allowance, your beneficiary might have to pay some tax. They can choose to take the money as a lump sum, or they can use it to buy an annuity, which gives them a regular income.
If you haven't named a beneficiary, the money will go into your estate and be distributed according to your will. If you don't have a will, the rules of intestacy will apply, which can sometimes lead to some... interesting results.
Defined Benefit Pensions: The Safe Bet
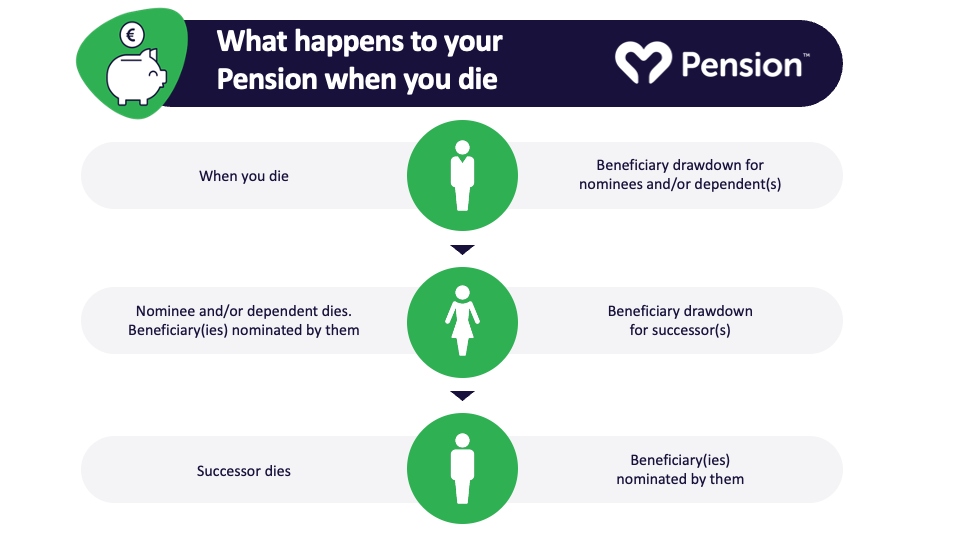
Defined benefit pensions, like final salary schemes, are a bit different. Instead of getting a lump sum, your beneficiary will get a regular, guaranteed income. This is usually paid to your spouse or civil partner until they die, then it might continue for your children until they reach 23 (or even longer if they're disabled).
 What Happens to My Pension When I Die? - MyPension
Again, if you haven't named a beneficiary, the money will go into your estate. But here's the kicker: defined benefit pensions can be worth a lot of money, so it's really important to make sure your will is up-to-date and that you've named your beneficiaries correctly.
What If You Want to Keep Your Pension Pot for Yourself?
If you're planning on living to 100 and you want to keep your pension pot for yourself, that's totally fine. Just make sure you're taking an income from your pension, either as a lump sum or a regular income. If you're not taking an income, the government might think you've forgotten about your pension and start charging you a hefty tax bill.
So, What's the Moral of the Story?
It's all about planning ahead, folks. Make sure you've got a will, name your beneficiaries, and keep your pension provider up-to-date with your details. It might not be the most exciting topic, but it's important. After all, you've worked hard for your pension, and you deserve to know that it's going to the right place when you're gone.
And hey, if you're still not sure about anything, don't hesitate to give your pension provider a call. They're there to help, and they've probably heard every question under the sun. Now, who's ready for that retirement tea?
