
What Is A Good Debt To Income Ratio
Alright, buddy, let's talk debt. I know, I know, it's not as exciting as the latest Netflix series, but stick with me, I promise to keep it fun. Let's dive into this debt-to-i...

Alright, buddy, let's talk debt. I know, I know, it's not as exciting as the latest Netflix series, but stick with me, I promise to keep it fun. Let's dive into this debt-to-income ratio thing, yeah?
What's the Big Deal with Debt-to-Income Ratio?
So, you've probably heard the term 'debt-to-income ratio' (DTI) thrown around, but what's the big deal about it? Well, it's like your personal finance report card. It's a quick, easy way to see how much of your income goes towards paying off your debts each month.
Think of it as a party (your income) and all your friends (your debts) are there, but you don't want your friends to outnumber you, right? That's what a high DTI can feel like.
Must Read
Calculating Your DTI: It's Like Math, But Fun!
Now, don't worry, I'm not going to make you dust off your old calculator. The formula is simple: take your monthly debt payments (like credit cards, loans, etc.) and divide them by your gross monthly income. Then, multiply that number by 100 to get a percentage.
For example, if you make $3,000 a month and your debt payments add up to $1,000, your DTI would be 33%. Easy peasy, right?
What's a Good DTI? Let's Set the Bar Low (Like Really Low)
Alright, so you've calculated your DTI. Now what? Well, lenders usually like to see a DTI of 43% or less. That means no more than 43% of your income should go towards paying off your debts. Why so low? Because they want to make sure you've got enough cash left over for other stuff, like food, shelter, and Netflix (priorities, right?).
But here's the thing, buddy. Just because lenders are okay with it, doesn't mean you should be. A lower DTI means more financial flexibility. It's like having a backup plan for when your friends (debts) start getting a little too rowdy at the party.
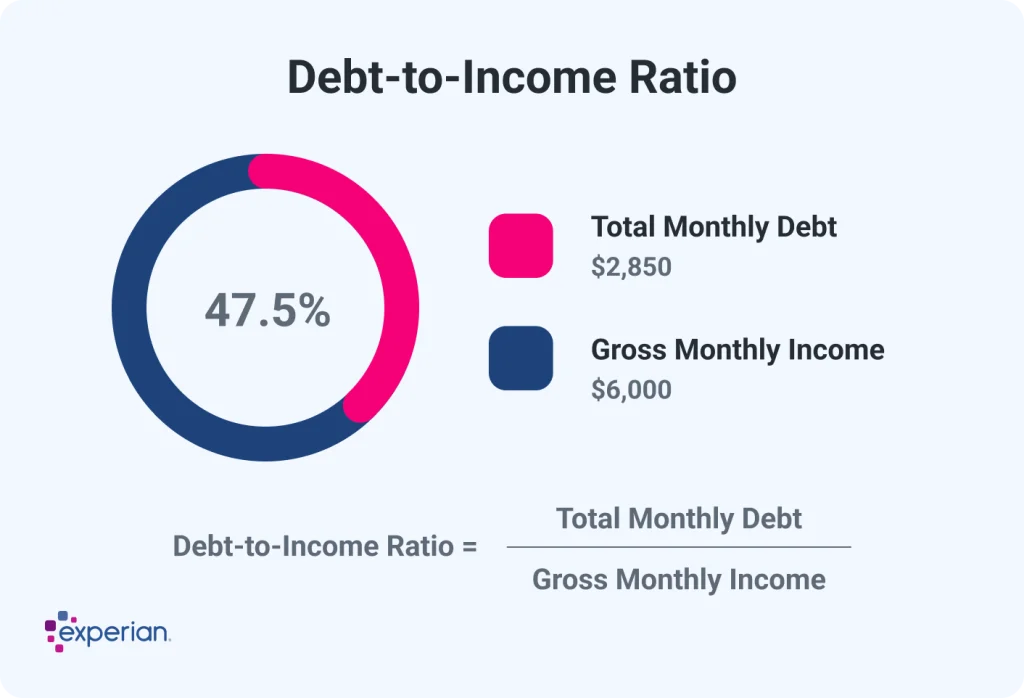 How is a DTI Ratio Calculated? - CEOColumn
How to Improve Your DTI: The Debt Diet
If your DTI is a little higher than you'd like, don't worry. It's like going on a diet, but for your finances. You can start by paying down your debts. Even small amounts can make a big difference. And remember, it's not about how much you make, but how much you keep. So, try to increase your income too, if you can.
And hey, don't forget to celebrate your wins. Every time you pay off a debt, treat yourself (within reason, okay?). You deserve it!
You're in the Driver's Seat: The Future is Bright!
So there you have it, the lowdown on debt-to-income ratio. It's not as scary as it sounds, is it? Remember, your DTI is just a number. It's not a reflection of your worth or your future. It's something you can control and improve.
Think of it like this: you're the driver, and your DTI is the GPS. It's there to guide you, but you're the one in control of the wheel. So, keep your eyes on the road, stay focused, and you'll get to where you want to be. And who knows, maybe one day you'll be able to look back and laugh at how far you've come.
Now, go forth, debt conqueror! You've got this!
