Does Universal Credit Count As Income For Mortgage
Universal Credit & Mortgages: A Match Made in Heaven? Hey there, curious mind! Let's dive into a question that's been buzzing around like a friendly bee: does Universal Credi...
Universal Credit & Mortgages: A Match Made in Heaven?
Hey there, curious mind! Let's dive into a question that's been buzzing around like a friendly bee: does Universal Credit count as income for a mortgage? Buckle up, 'cause we're about to make learning about finance as fun as a rollercoaster ride!
First things first: What's Universal Credit?
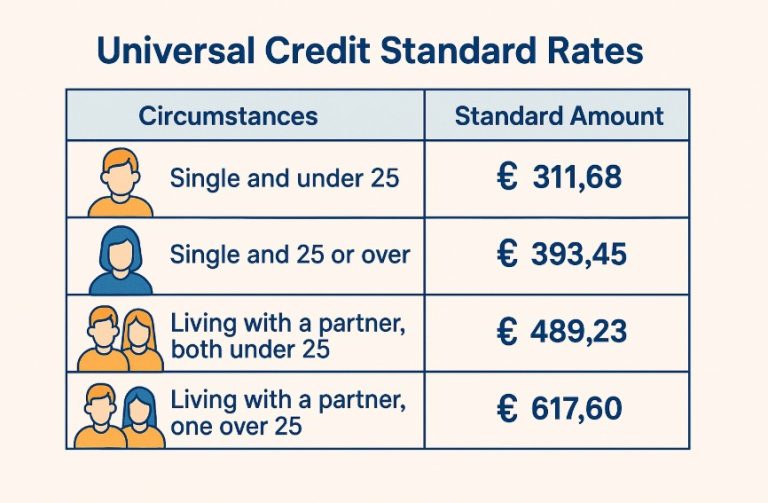
Imagine Universal Credit as the fairy godmother of benefits. It's a monthly payment that helps with living costs if you're on a low income, out of work, or unable to work. It's like having a secret sidekick that's always got your back!
Now, Let's Talk Mortgages!
Mortgages, oh mortgages. They're like the big, scary dragon guarding the castle of homeownership. But don't worry, we're going to slay this dragon together!
Must Read
When you apply for a mortgage, lenders want to know if you can handle the monthly payments. They look at your income – that's the money you bring home from your job, or in this case, Universal Credit.
Universal Credit: The Income Whisperer
Here's where things get interesting. Universal Credit can indeed count as income for a mortgage, but it's not as simple as adding it to your paycheck. Lenders usually look at the maximum amount you could get, not what you're actually receiving. It's like they're playing a game of 'let's imagine the best-case scenario'!
But wait, there's more! Lenders also consider other income you might have, like a partner's salary or rental income. It's like they're making a big, delicious financial stew, and Universal Credit is one of the tasty ingredients!
How Much Can You Borrow?
Now, let's talk about how much you can borrow. It's like trying to guess how many candies are in a jar – it's all about the estimate!
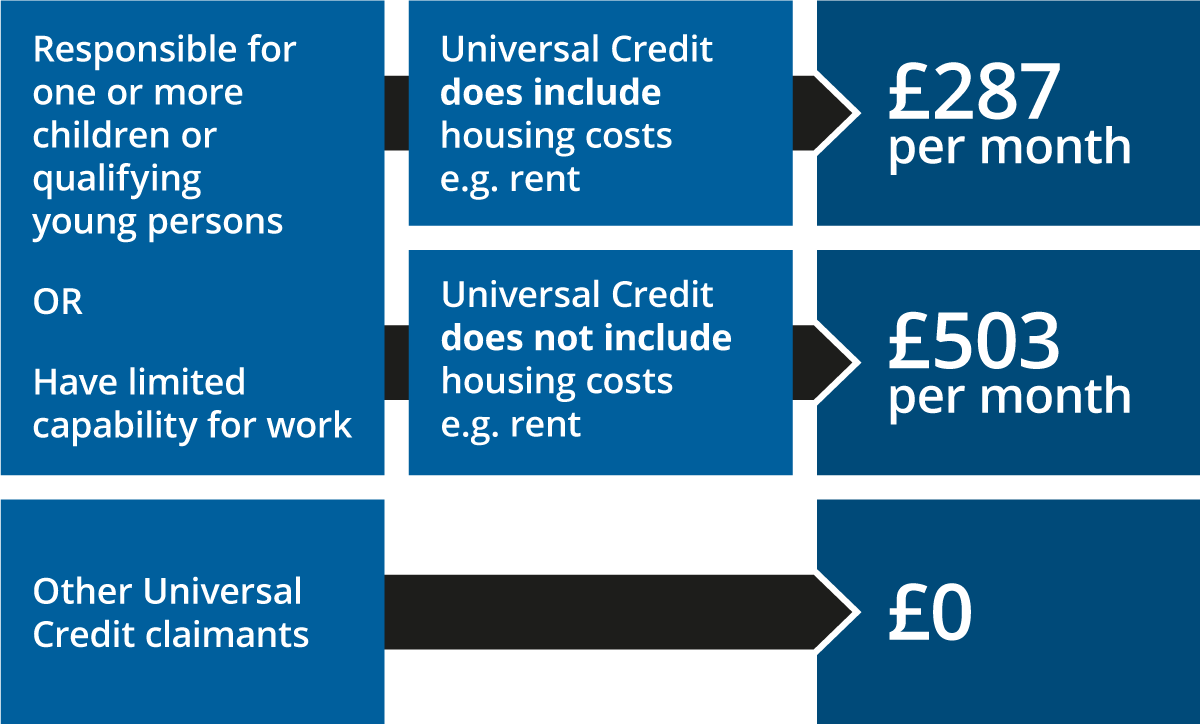
Lenders usually use a multiple of your income to work out how much they'll lend you. So, if you're getting Universal Credit, they'll use that to calculate. For example, if you're eligible for the maximum Universal Credit and you're applying for a mortgage with a lender that uses a 4.5x income multiple, you could potentially borrow around £168,000 (based on the current maximum Universal Credit for a single person). Not bad, huh?
 What Are The Changes With Universal Credit at Brittany Cray blog
But Wait, There's More!
Remember, every lender is different, and they might have their own rules about Universal Credit. Some might not count it at all, while others might have special criteria. It's like they're all speaking different languages, and you need a translator – that's where a mortgage broker comes in handy!
So, Should You Apply?
Now that we've got the lowdown on Universal Credit and mortgages, you might be wondering if you should apply. The answer? It depends!
If you're thinking about it, it's a great idea to speak to a financial advisor or mortgage broker. They can help you figure out if you're ready for the mortgage rollercoaster, and if Universal Credit can give you that extra boost you need.
Remember, Knowledge is Power!
Learning about finance can feel like trying to solve a puzzle with a million pieces. But with each piece you find, you're one step closer to the big picture. So, keep exploring, keep asking questions, and most importantly, keep having fun!
And who knows? You might just find that Universal Credit is the key to unlocking your homeownership dreams. So, go on, give it a try – you've got this!
