
What Happens To My Pension If I Die
Alright, picture this: You're cruising down the highway of life in your shiny new pension plan convertible, top down, wind in your hair, feeling like a million bucks. Suddenly...
Alright, picture this: You're cruising down the highway of life in your shiny new pension plan convertible, top down, wind in your hair, feeling like a million bucks. Suddenly, you hit a pothole - a big one. You've just been asked "What happens to my pension if I kick the bucket?"
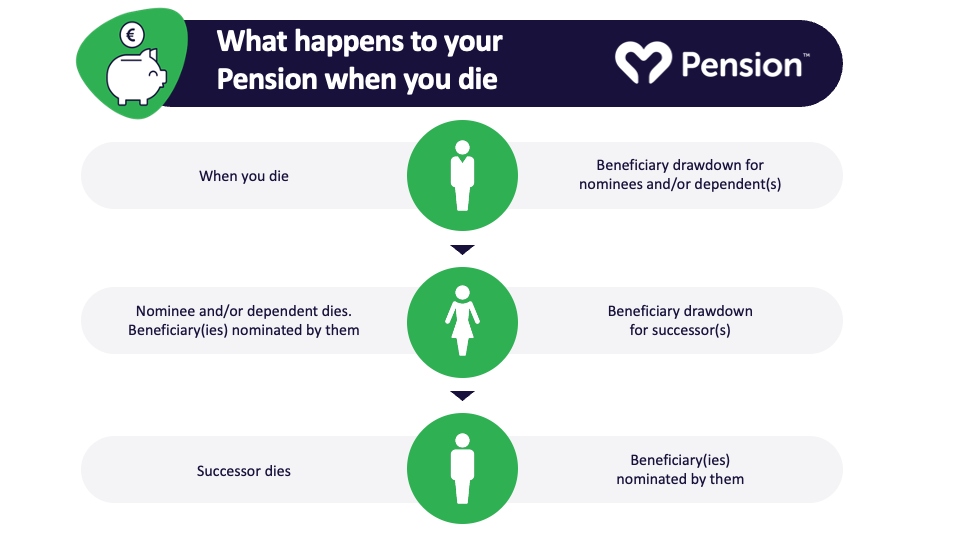
First things first, let's talk beneficiaries.
Imagine your pension plan is a fancy dinner party, and you're the host. You've invited some special guests - your beneficiaries. These are the lucky folks who'll inherit your pension if you shuffle off this mortal coil. You can choose anyone: your spouse, kids, that one friend who always brings the best wine. Just make sure to keep your beneficiary forms up to date. After all, you wouldn't want your pension going to that ex who still has a key to your house, would you?
Now, let's talk pension types. It's like choosing a main course.
You've got a few options here, each with its own twist on what happens when you're no longer around to enjoy the meal.
Must Read
Defined Benefit Plans: The Buffet.
With a defined benefit plan, your employer promises you a certain monthly payment in retirement. It's like they're saying, "Here's your lifetime supply of pension goodness, enjoy!" If you die before you start receiving benefits, your beneficiary gets a lump sum - think of it as a 'Sorry you're gone, but here's a big check' package. If you're already receiving benefits when you kick the bucket, your beneficiary might get a continuing payment, but it depends on the plan.
Defined Contribution Plans: The Food Truck.
In a defined contribution plan, like a 401(k), you and your employer contribute to your account, and the balance grows over time. If you die before retirement, your beneficiary gets the whole kit and caboodle - the entire account balance. If you die after retiring, it gets a bit trickier. Some plans allow your beneficiary to continue receiving payments, while others require them to take the entire amount at once. It's like choosing between a to-go box and a doggy bag.
Annuities: The Cooking Class.
Annuities are like a pension plan you buy from an insurance company. You give them money, and they promise to pay you a certain amount each year until you die. If you die before you've received all your payments, your beneficiary might get the remaining balance. But here's where it gets interesting: some annuities offer a 'period certain' option, which guarantees payments for a set number of years, even if you die. It's like signing up for a cooking class that lasts 20 years, and if you drop out early, your beneficiary gets to finish the course.
 PPT - Pension Seminar for non-teaching pension plan members PowerPoint
Taxes: The Bill at the End of the Meal.
Now, let's talk about the elephant in the room - taxes. When your beneficiary inherits your pension, they might have to pay Uncle Sam a visit. The amount they pay depends on the type of pension and how long you've been receiving benefits. But here's a fun fact: if your beneficiary is your surviving spouse, they can roll over your pension into their own IRA, delaying taxes until they start taking distributions. It's like getting a free appetizer to make up for the big bill that's coming.
So, what's the moral of the story?
Your pension plan is like a fancy dinner party - you want to make sure you've invited the right guests (beneficiaries), you've chosen the right main course (pension type), and you've got a plan for the bill (taxes). And most importantly, you want to make sure you've updated your RSVP - keep your beneficiary forms up to date! Because let's face it, none of us want our pension going to that ex who still owes us money for the last dinner party.
And there you have it - a fun, casual, and hopefully not too painful explanation of what happens to your pension when you die. Now, who's ready for dessert?
